Why an Arizona Construction Loan Could Be Your Path to a Custom Desert Home
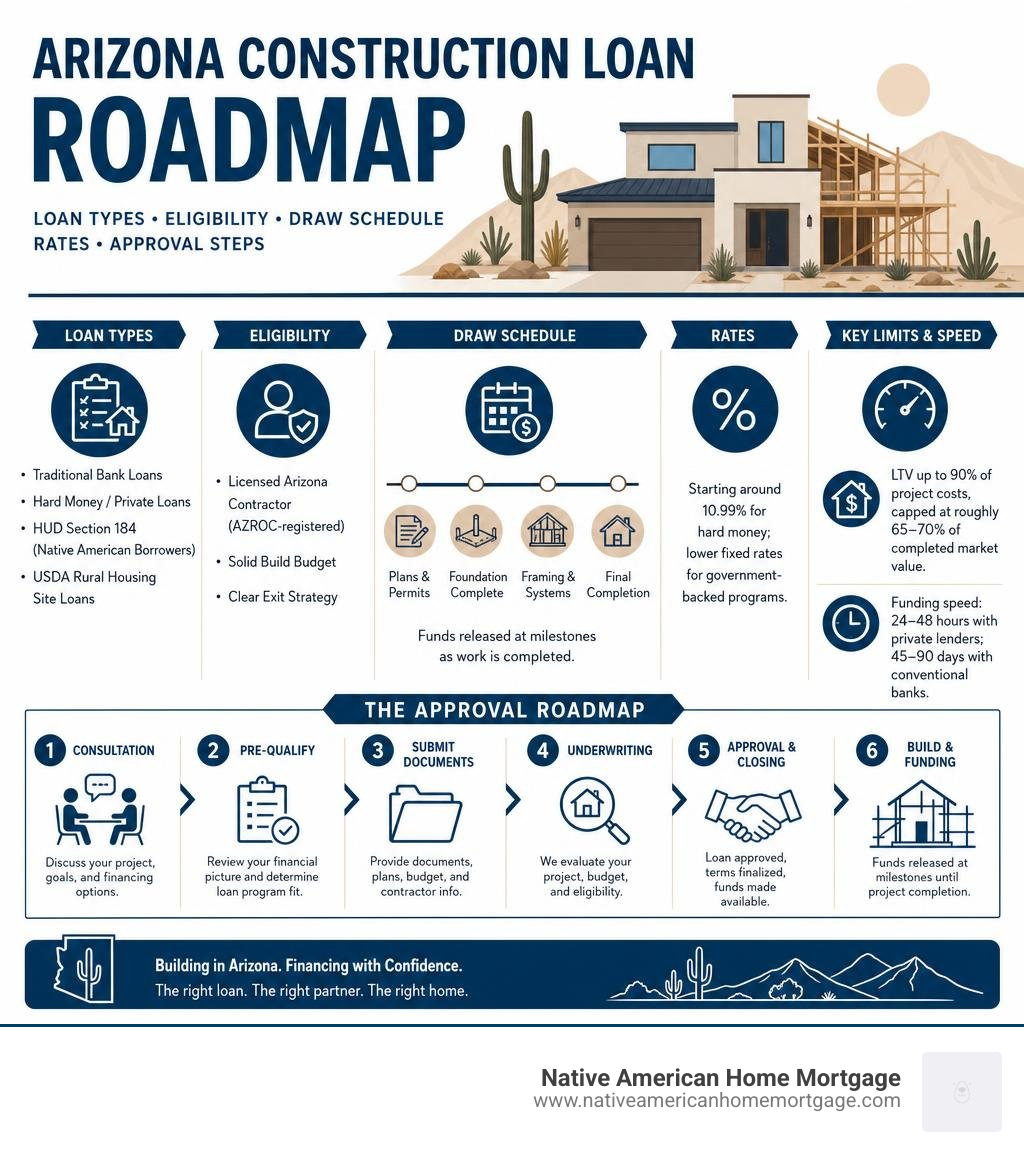
An arizona construction loan is a short-term financing tool that lets you fund the building of a new home or major renovation — from raw land purchase all the way through to a finished, move-in-ready property. Here’s a quick snapshot of what you need to know:
- Loan types: Traditional bank loans, hard money/private loans, HUD Section 184 (for Native American borrowers), and USDA Rural Housing Site Loans
- Typical rates: Starting around 10.99% for hard money; lower fixed rates for government-backed programs
- LTV limits: Up to 90% of project costs, capped at roughly 65–70% of completed market value
- Funding speed: As fast as 24–48 hours with private lenders; 45–90 days with conventional banks
- Key requirement: A licensed Arizona contractor (AZROC-registered), a solid build budget, and a clear exit strategy
Arizona’s booming housing market — from Phoenix suburbs like Queen Creek and Buckeye to rural tribal communities — has created strong demand for fast, flexible construction financing. But the landscape can be confusing. Bank underwriting is slow. Terms vary widely. And if you’re building on tribal or trust land, most conventional lenders simply don’t know how to help.
I’m Dale Gremillion, a Senior Loan Officer with over 20 years of mortgage industry experience, and I specialize in helping Native American borrowers navigate arizona construction loan programs — including the HUD Section 184 Indian Housing Loan Guarantee Program — to build on trust land and tribal property with terms conventional lenders can’t match. In the sections ahead, I’ll walk you through every loan type, qualification requirement, and draw process you need to know.
Understanding Your Options for an Arizona Construction Loan
When financing a custom residential build or major structural overhaul in Arizona, selecting the right financing pathway is critical. Whether you are acquiring raw land in Coconino County, building a custom residence in Scottsdale, or developing an accessory dwelling unit (ADU) in Tucson, the structured funding product you choose dictates your timeline, interest costs, and cash flow.
An arizona construction loan provides short-term capital designed specifically to cover land acquisition, architectural plans, permits, labor, and building materials. Unlike traditional fixed-rate mortgages that disburse a single lump sum at closing, construction financing operates as a specialized line of credit disbursed in stages as construction milestones are verified.
Projects eligible for construction financing across Arizona include:
- Ground-up single-family custom home builds
- Infill lot developments replacing older housing stock
- Major structural gut renovations exceeding 50% of completed value
- New spec home developments for real estate investors
- Residential builds on sovereign tribal or trust land
Comparing Traditional and Hard Money Arizona Construction Loan Products
Borrowers typically choose between traditional institutional bank loans and private hard money financing depending on project speed, underwriting requirements, and leverage.
Conventional bank loans rely heavily on borrower credit history, tax returns, and comprehensive financial underwriting. While banks offer lower interest rates, their approval process takes 45 to 90 days. Furthermore, traditional banks frequently mandate rigid pre-sale metrics or strict caps on active builder projects.
In contrast, private hard money construction financing focuses primarily on asset collateral, project viability, and After-Repair Value (ARV). Private lenders evaluate the prospective market value of the home and the quality of the building plan rather than requiring extensive W-2 tax history. Hard money construction loans can provide fast written loan decisions within 24 hours and close funding within 24 to 48 hours of receiving a clear preliminary title report.
| Feature | Conventional Bank Construction Loan | Private / Hard Money Construction Loan |
|---|---|---|
| Primary Underwriting Focus | Credit score, W-2 income, debt ratios | Property ARV, land collateral, project scope |
| Approval & Funding Speed | 45 to 90 days | 24 to 48 hours following preliminary title |
| Typical Interest Rates | Prevailing prime-based market rates | Starting around 10.99% (8% – 12% range) |
| Maximum Loan-to-Cost (LTC) | 70% – 80% total project cost | Up to 90% total project cost |
| Max Loan-to-Value (LTV) | 65% – 70% of prospective market value | Up to 69% of completed market value |
| Income / Credit Verification | Full documentation (tax returns, balance sheets) | Asset-based options available without tax returns |
How to Secure an Arizona Construction Loan with HUD Section 184
For Native American and Alaska Native tribal members building a home in Arizona, standard construction loan options often present hurdles—especially when building on reservation land or tribal trust land. Traditional banks rarely offer construction financing on sovereign land due to title sovereignty and land status complexities.
That is where specialized federal financing comes in. Through our comprehensive Guide to Native Homeownership, we help eligible borrowers leverage the HUD Section 184 Indian Housing Loan Guarantee Program to fund single-close or two-step construction builds.
HUD Section 184 loans are engineered specifically for Native American borrowers, federally recognized tribes, and tribally designated housing entities. Key construction financing benefits include:
- Low down payment requirements (as low as 2.25% on construction builds over $50,000)
- Flexible credit underwriting tailored to Native homebuilders
- Full capability to finance single-family builds on tribal trust land, allotted trust land, or fee-simple land within approved tribal jurisdictions
Navigating tribal housing authority approvals and Bureau of Indian Affairs (BIA) site status requires experienced guidance. By reviewing HUD 184 State Approvals and evaluating published HUD 184 Maximum Limits, Native borrowers can secure complete land development and building capital tailored to their county location. We also encourage reviewing The Complete Guide to Section 184 Loan Qualifications and Guidelines and Demystifying Section 184: Your Path to Affordable Tribal Homeownership to prepare your paperwork seamlessly.
USDA Rural Housing Site Development Programs
For community organizations, non-profits, and housing developers creating affordable housing sites in eligible rural areas of Arizona, federal programs such as USDA Rural Housing Site Loans in Arizona provide essential pre-development funding.
The USDA Rural Development framework offers two primary site development financing vehicles:
- Section 523 Site Loans: Designed specifically to acquire and develop land plots for homes constructed using the Self-Help build methodology. These loans carry a fixed 3% interest rate.
- Section 524 Site Loans: Available to buy and prepare housing sites for low-income families (50% to 80% of Area Median Income) and moderate-income families (up to 115% of AMI) without restriction on the construction method. These feature below-market fixed interest rates.
Both Section 523 and Section 524 site development loans carry 5-year loan terms, providing public entities and recognized tribes revolving loan funds to establish civil infrastructure, complete site grading, and lay utilities across rural Arizona communities.
Borrower Eligibility and Contractor Qualifications in Arizona
Qualifying for an arizona construction loan requires demonstrating financial stability and pairing your build with qualified project partners. Lenders evaluate deal structure using the “3 C’s of Real Estate Lending”: Credit history, Capacity to pay, and Collateral quality.
Whether you are seeking institutional financing or private asset-based capital, lenders require documented assurance that your construction project will be executed safely, legally, and within budget.
Financial Metrics and Approval Ratios
Underwriters analyze key financial ratios during the application phase to ensure project sustainability across every construction phase:
- Loan-to-Value (LTV) Ratios: Lenders evaluate prospective market value upon completion. During the Construction Period, maximum funding is commonly capped at 70% of prospective market value (PMV) or up to 69% of completed After-Repair Value (ARV). Long-term permanent periods typically cap at 65% to 80% LTV depending on program parameters.
- Loan-to-Cost (LTC): Private construction financing can fund up to 90% of total project costs, requiring the borrower or investor to contribute at least 10% in equity or land value.
- Debt Service Coverage Ratio (DSCR): For income-producing or investment builds, lenders often covenant that a minimum DSCR of 1.50 to 1.0 must be maintained across the loan life.
- Capacity & Reserve Liquidity: Borrowers must demonstrate sufficient cash reserves to cover soft costs, permit fees, and initial draw outlays prior to milestone disbursements.
AZROC Compliance and Permitting Mandates
Your choice of general contractor is just as critical to loan approval as your credit profile. Lenders enforce strict builder qualification checklists to safeguard construction capital.
In Arizona, general contractors must meet strict statutory standards:
- Active AZROC License: Builders must hold an active license with the Arizona Registrar of Contractors (AZROC) in good standing with no unresolved disciplinary violations.
- Liability Insurance Coverage: Contractors must maintain general liability coverage of at least $1,000,000 combined single limit.
- Bonding Requirements: AZROC mandates statutory commercial contractor bonding, especially for residential build scopes exceeding $50,000.
- Permit Processing Timelines: Single-family residential plan reviews and building permit issuances across Phoenix, Tempe, and East Valley municipalities typically take 2 to 6 weeks. Projects located in unincorporated Maricopa or Pinal counties may require additional flood control or septic review buffers.
A valid local municipal permit and an executed, fixed-price construction contract with an AZROC-licensed builder are mandatory prerequisites before loan closing and initial draw funding.
Navigating the Construction Draw Schedule and Project Execution
Construction loan funds are not handed over as a lump sum. Instead, capital is held in escrow and released incrementally through a milestone-based construction draw schedule. This process protects both borrower and lender, ensuring funds are disbursed only as physical work is verified.
The 5-Stage Construction Draw Milestone Structure
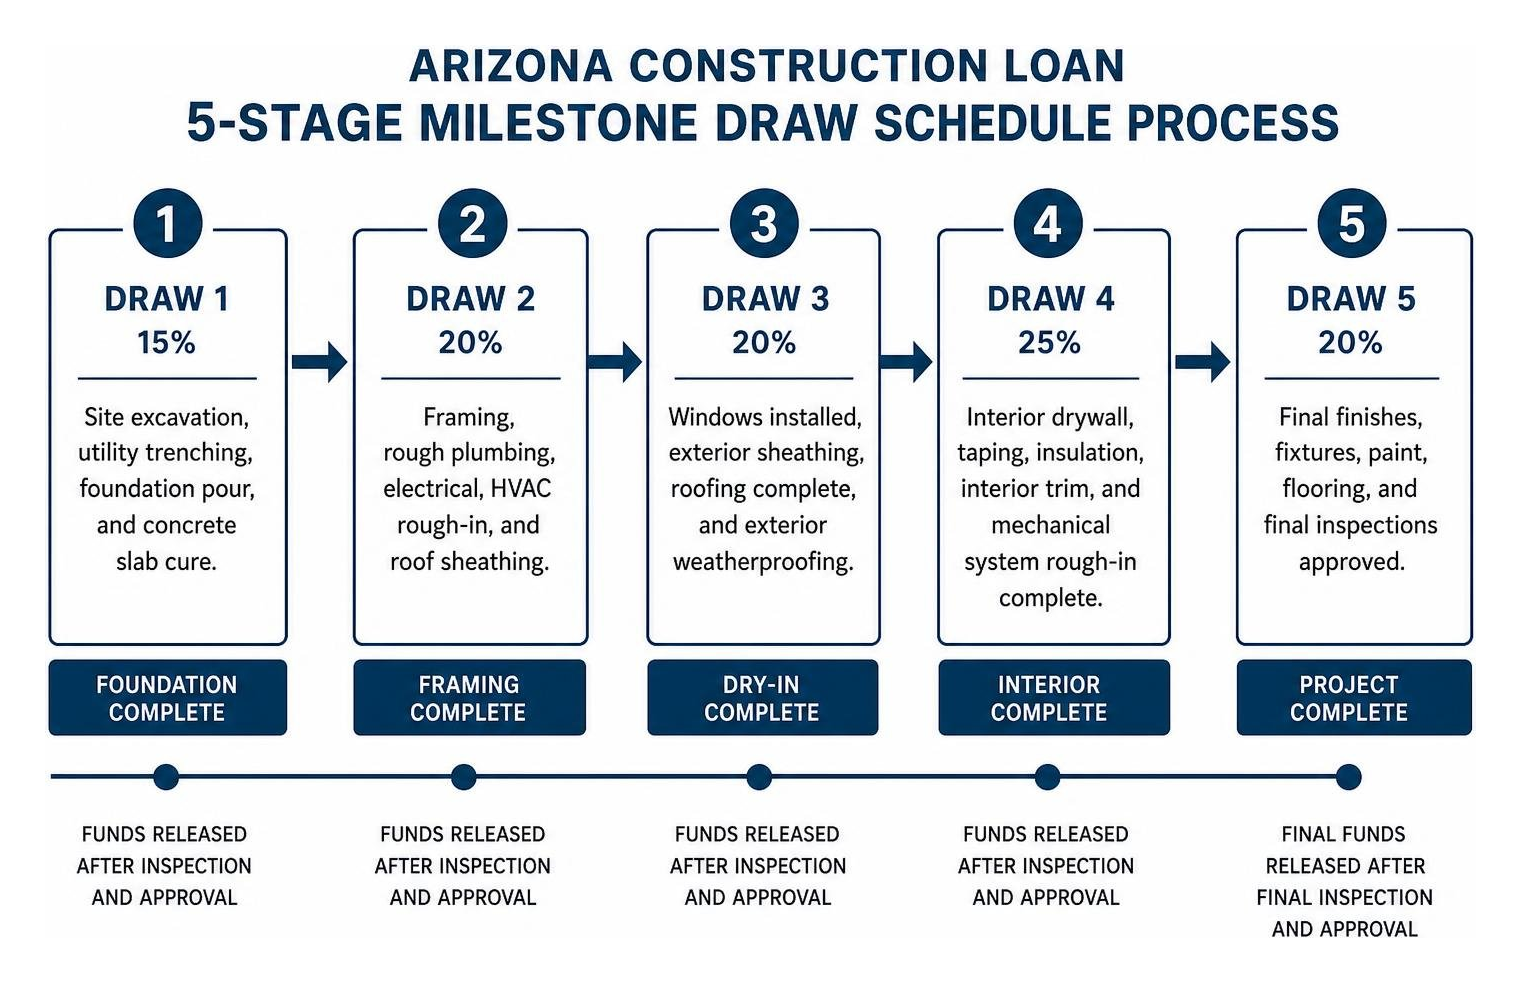
A standard 5-draw schedule for a ground-up single-family home build in Arizona allocates construction funds across key construction milestones:
- Draw 1 (15% Allocation): Site excavation, utility trenching, foundation pour, and concrete slab cure.
- Draw 2 (25% Allocation): Structural framing, wall sheathing, roof truss installation, and exterior weatherproofing.
- Draw 3 (25% Allocation): Rough plumbing, electrical wiring, HVAC ductwork, insulation, and drywall installation.
- Draw 4 (20% Allocation): Interior finishes, cabinetry, tile installation, exterior stucco/paint, and major mechanical trim-out.
- Draw 5 (15% Allocation): Final cosmetic trim, site grading, final municipal building inspection, release of final lien waivers, and issuance of the Certificate of Occupancy.
When a builder reaches a milestone, a formal draw request is submitted. A third-party property inspector visits the Arizona job site to verify completed work, check lien releases from subcontractors, and authorize the release of funds.
Loan Balancing and Legal Covenants
To maintain financial stability, formal loan agreements include strict legal covenants. Reviewing Standard Arizona Construction Legal Terms reveals essential mechanisms designed to keep builds on track:
- Loan Balancing Mechanics: A construction loan is considered “in balance” when the undisbursed portion of the loan budget is sufficient to cover all remaining hard and soft costs. If cost overruns or material price increases cause a deficit, the loan goes out of balance. The borrower must deposit additional equity into a borrower funds account within 15 days of written notice to bring the loan back into balance.
- Interest Reserve Accounts: Many short-term construction loans establish an interest reserve line within the loan amount. Monthly interest-only payments are drawn directly from this reserve during active construction, protecting borrower cash flow until the build finishes.
- Change Order Approval Thresholds: Lenders enforce strict oversight on design revisions. Individual change orders exceeding $100,000 or cumulative change orders exceeding $250,000 require formal written approval from the lender before work begins.
Interest Rates, Terms, and Approval Speeds
Because construction financing carries unique risks during structural assembly, loan terms differ from standard 30-year mortgages.
Key financial characteristics of an arizona construction loan include:
- Loan Duration: Short-term structure ranging from 1 to 3 years (12-month construction period, with optional extension terms or multi-phase transitions).
- Payment Structure: Interest-only payments calculated strictly on the drawn loan balance, not the total committed line amount.
- Interest Rates: Private hard money construction rates start around 10.99% (typically ranging from 8% to 12%), reflecting rapid capital deployment and flexible underwriting. Government-backed programs like HUD Section 184 offer competitive standard fixed market rates.
- Loan Amounts: Flexible funding limits ranging from $50,000 for small builds or additions up to $25,000,000 for large-scale developments.
When time is critical—such as acquiring an infill lot in Phoenix before a competing bid arrives—private lenders can approve funding in as little as 1 hour and disburse funds within 48 hours of title review. Traditional institutional loans offer lower interest costs but require a 45 to 90-day processing window.

Frequently Asked Questions About Arizona Construction Financing
What is the fastest way to fund an Arizona construction loan?
The fastest way to secure construction capital in Arizona is through an asset-based private hard money lender. By focusing on site value, After-Repair Value (ARV), and fixed building plans rather than deep tax history, private lenders can issue initial written loan offers within 24 hours. Funding can occur in as little as 24 to 48 hours once a clear preliminary title report is issued.
Can I build a custom home on tribal or trust land in Arizona?
Yes! Building on sovereign tribal or trust land in Arizona is entirely feasible using specialized federal loan programs. Traditional banks often hesitate due to sovereign land title restrictions, but through our FHA and Section 184 Guide, Native American borrowers can secure specialized single-close construction financing. This allows seamless land leasehold approval, site preparation, and home construction on trust lands across Arizona.
How do loan-to-value (LTV) limits work for ground-up construction in Arizona?
LTV limits for ground-up construction are calculated based on the completed appraisal value (prospective market value or ARV) rather than raw land cost alone. Most lenders cap funding at 69% to 70% of the completed prospective market value, while allowing up to 90% coverage of total project construction costs.
Conclusion
Building your custom desert oasis in Arizona is an exciting journey, but success depends on selecting the right financing structure. Whether you choose a fast private construction loan to capitalize on a market opportunity or leverage HUD Section 184 financing to build on sovereign tribal land, securing experienced guidance makes all the difference.
At Native American Home Mortgage, we specialize in helping homebuilders, families, and tribal members navigate complex construction guidelines across Arizona, New Mexico, Utah, and Colorado. By Unlocking HUD 184 Benefits, we empower you to turn architectural plans into reality with lower down payments and competitive terms.
Ready to start building? Contact our team of experienced loan specialists at Native American Home Mortgage today to review your project plans, evaluate your loan eligibility, and take the first step toward financing your Arizona build!