Home Loan Interest Rates at a Glance
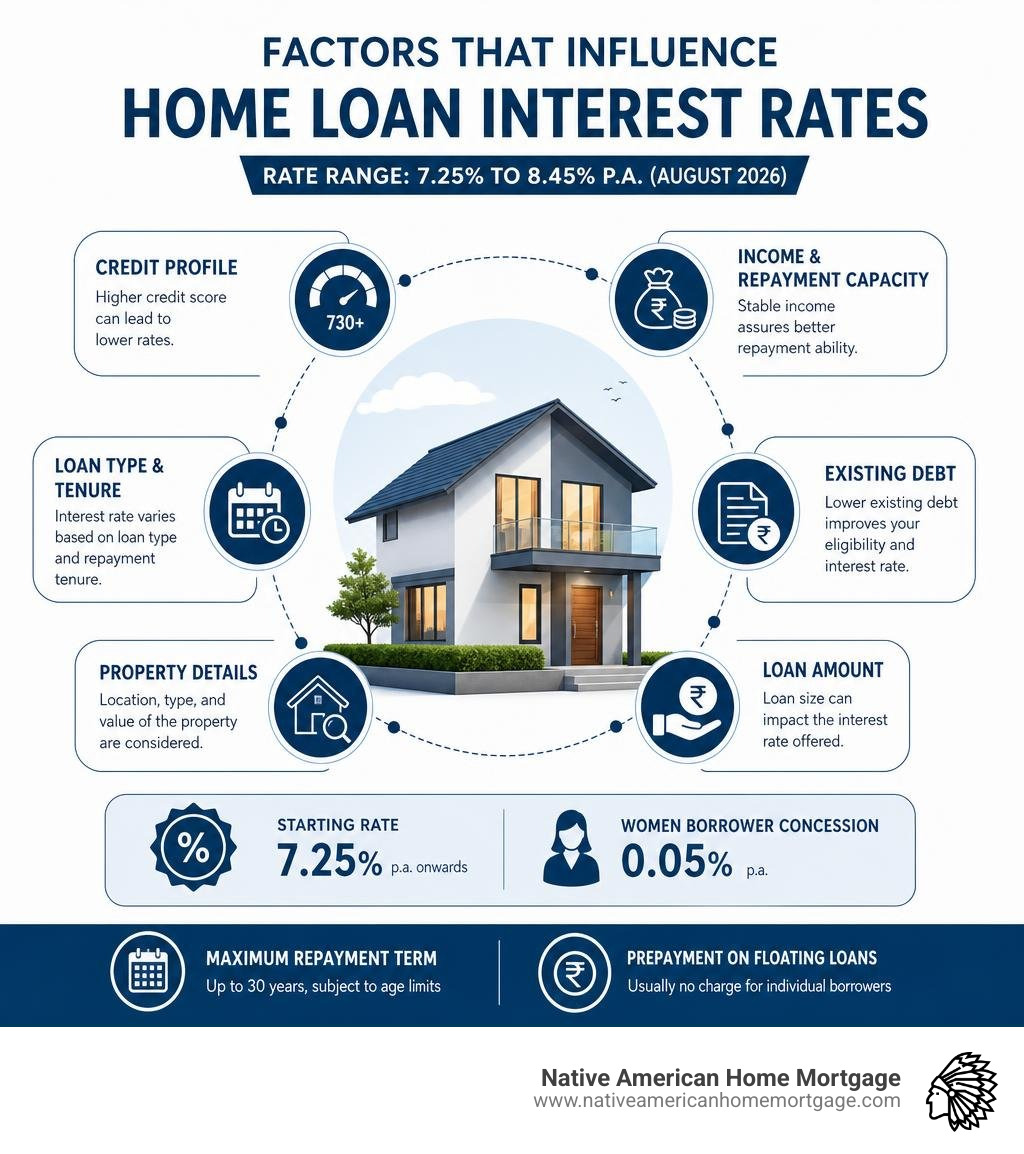
Competitive home loan interest rates vary based on a borrower’s credit profile, loan amount, down payment, and chosen loan program.
| Key detail | Program Information |
|---|---|
| Rate structure | Fixed and adjustable rate options |
| Typical rate factors | Credit score, LTV, income, debt ratio |
| Benchmark indices | Benchmark prime and market index rates |
| Specialized concessions | Benefits for eligible tribal citizens and first-time buyers |
| Maximum repayment term | Up to 30 years |
| Prepayment terms | Flexible terms depending on loan structure |
Mortgage interest rates fluctuate based on market conditions, economic benchmarks, and individual qualifications. The final rate offered depends directly on your credit score, household income, existing obligations, property evaluation, and loan program selection.
I am Dale Gremillion, a Senior Loan Officer and Producing Branch Manager with more than 25 years of residential lending experience across conventional, FHA, HUD 184, VA, and USDA financing. This guide breaks down mortgage interest rate structures while focusing on helping Native American borrowers and homebuyers understand financing choices built around their communities, property goals, and financial realities.
Explore related resources:
Current Home Loan Interest Rate Structures and Key Benchmark Rates
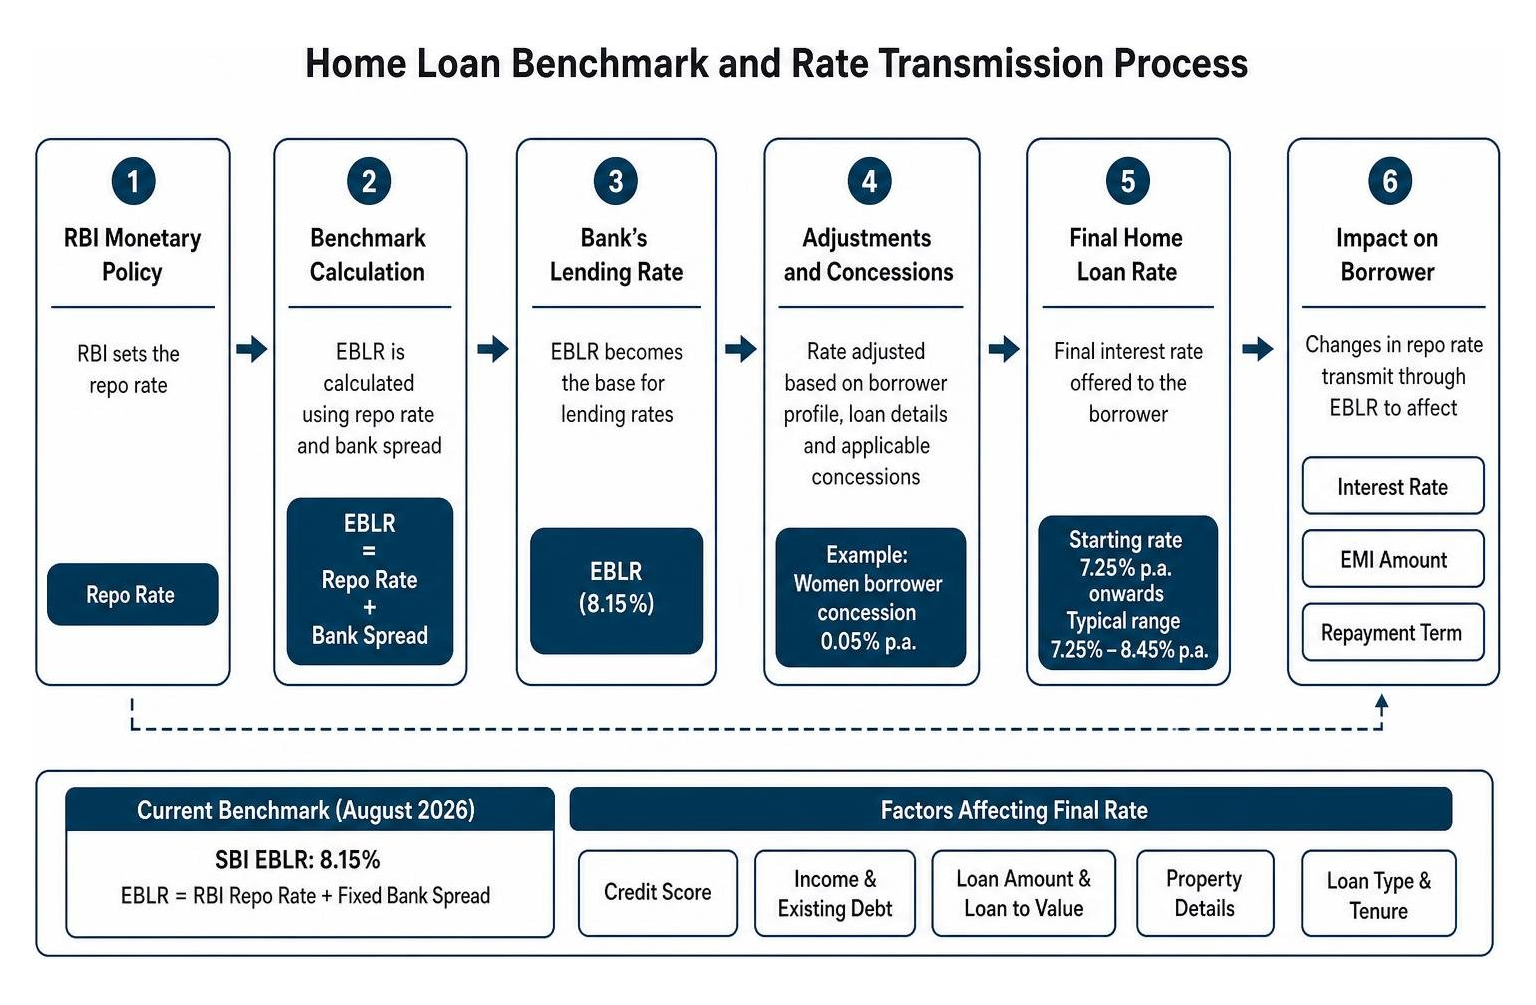
When evaluating how mortgage rates are structured, it is essential to understand whether you are opting for a fixed-rate or adjustable-rate mortgage (ARM). Variable or adjustable rates are governed by benchmark pricing engines tied to broader market rates. Calculating interest on daily or monthly principal balances ensures that every payment reduces the principal debt, lowering long-term interest accrual over a 15 or 30-year term.
Interest rate tiers vary across loan types based on risk assessments, borrower credit scores, occupational stability, and loan-to-value ratios.
Understanding Benchmark Indices and Variable Interest Rates
To understand why variable loan rates adjust over time, borrowers must look at underlying benchmark indices. Standard adjustable rate mortgages combine an index rate with a lender margin:
Interest Rate = Market Benchmark Index + Fixed Margin
When benchmark indices shift, variable rates update accordingly. This market mechanism influences long-term interest costs, making fixed-rate alternatives attractive for borrowers seeking predictable monthly payments.
Impact of Credit Scores on Mortgage Rates
Your credit score is one of the most significant factors determining the final interest rate tier for which you qualify. Lenders use risk-based pricing to reward creditworthy applicants with lower interest margins.
- Credit Score 780 and above: Qualify for top-tier interest rates and lower insurance premiums.
- Credit Score 720 – 779: Receive strong competitive pricing with minor risk adjustments.
- Credit Score 660 – 719: Standard rate tiers apply, with moderate rate adjustments.
- Credit Score 620 – 659: Qualify under specialized programs like FHA or HUD Section 184 with modified underwriting rules.
Improving your credit profile prior to application remains one of the most effective ways to lower total borrowing costs.
Home Loan Programs, Rates, and Options

Lenders offer several mortgage options designed for distinct financial situations, property types, and homebuyer needs.
- Conventional Mortgages: Standard financing suited for borrowers with established credit and down payment flexibility.
- FHA Loans: Government-backed loans offering lower credit score thresholds and low down payment requirements.
- VA Loans: Exclusive benefits for eligible military service members, veterans, and surviving spouses featuring zero down payment options.
- USDA Loans: Targeted financing for qualifying rural and suburban properties with favorable terms.
Special Loan Options for Native American Homebuyers and Specialized Groups
For Native American borrowers and tribal citizens, specialized federal programs offer tailored financing structures with flexible credit evaluations and low down payments.
key program advantages include:
- Low down payment requirements (as low as 2.25%).
- Flexible underwriting criteria tailored to tribal land and fee-simple properties.
- Reduced monthly mortgage insurance costs.
Over the life of a loan, securing favorable government-backed terms saves thousands of dollars in interest and insurance fees.
For specialized native homeownership options across the United States, including government-backed Native American mortgage solutions, explore programs such as the Section 184 Indian Home Loan Guarantee Program and state homeownership resources like Homeownership Loans – State of Delaware .
Fees, Processing Charges, and Repayment Calculations
Evaluating a home loan requires looking beyond the nominal interest rate. Closing costs, origination fees, appraisal charges, and loan terms directly impact total overall expenditure.
| Loan Amount | Sample Interest Rate | Loan Tenure | Estimated Monthly Payment | Total Interest Payable | Total Cost (Principal + Interest) |
|---|---|---|---|---|---|
| $250,000 | 6.25% | 20 Years | $1,827 | $188,574 | $438,574 |
| $350,000 | 6.50% | 20 Years | $2,609 | $276,275 | $626,275 |
| $500,000 | 6.25% | 20 Years | $3,655 | $377,149 | $877,149 |
Borrowers can analyze customized scenarios using standard mortgage payment tools.
Closing Costs, Origination, and LTV Ratios
Beyond basic monthly principal and interest, upfront charges apply during mortgage origination:
- Origination & Processing Fees: Typically range between 0.5% to 1.0% of the loan amount depending on lender guidelines.
- Prepayment Terms: Most conventional and government-backed residential loans carry zero prepayment penalties for early payoff.
- Loan-to-Value (LTV) Ratios:
- Higher down payments lower your LTV ratio, reducing interest premiums and eliminating private mortgage insurance (PMI) requirements on conventional loans when reaching 80% LTV.
Calculating Monthly Payments
Monthly principal and interest payments rely on standard amortization calculations:
EMI = [P x r x (1+r)^n] / [(1+r)^n - 1]
Where P represents principal, r represents monthly interest rate, and n represents total term months. Choosing a shorter term increases monthly payments but dramatically reduces cumulative interest costs.
Frequently Asked Questions About Home Loans
What determines the starting interest rate for a home loan?
Starting mortgage interest rates depend on broader economic indicators, benchmark indices, applicant credit scores, down payment amounts, loan-to-value ratios, and specific loan program guidelines.
Are there prepayment penalties on residential home loans?
Most modern residential mortgages, including HUD 184, FHA, VA, and conventional loans, do not carry prepayment penalties. Borrowers can make extra principal payments or pay off their mortgage balance early without penalty fees.
How do benchmark interest rate shifts affect mortgage payments?
For adjustable-rate mortgages, shifts in benchmark market rates directly impact interest calculations upon rate adjustment dates. Fixed-rate mortgages remain completely unaffected by market rate changes throughout the loan term.
Conclusion
Understanding home loan rate dynamics empowers buyers to make informed financial choices. By maintaining a strong credit profile, choosing an appropriate term, comparing specialized loan options, and leveraging dedicated buyer programs, you can minimize total long-term borrowing costs.
At Native American Home Mortgage, we believe that secure homeownership starts with expert guidance and transparent information. Whether you are exploring specialized native mortgage solutions, HUD 184 home loans, or navigating general mortgage rate mechanics, our team is dedicated to helping you achieve your homeownership goals with confidence.