Indian Bank Housing Finance at a Glance
A house loan in Indian Bank can help eligible residents, NRIs, salaried workers, self-employed borrowers, and pensioners finance a home purchase, construction, extension, renovation, or eligible loan transfer.
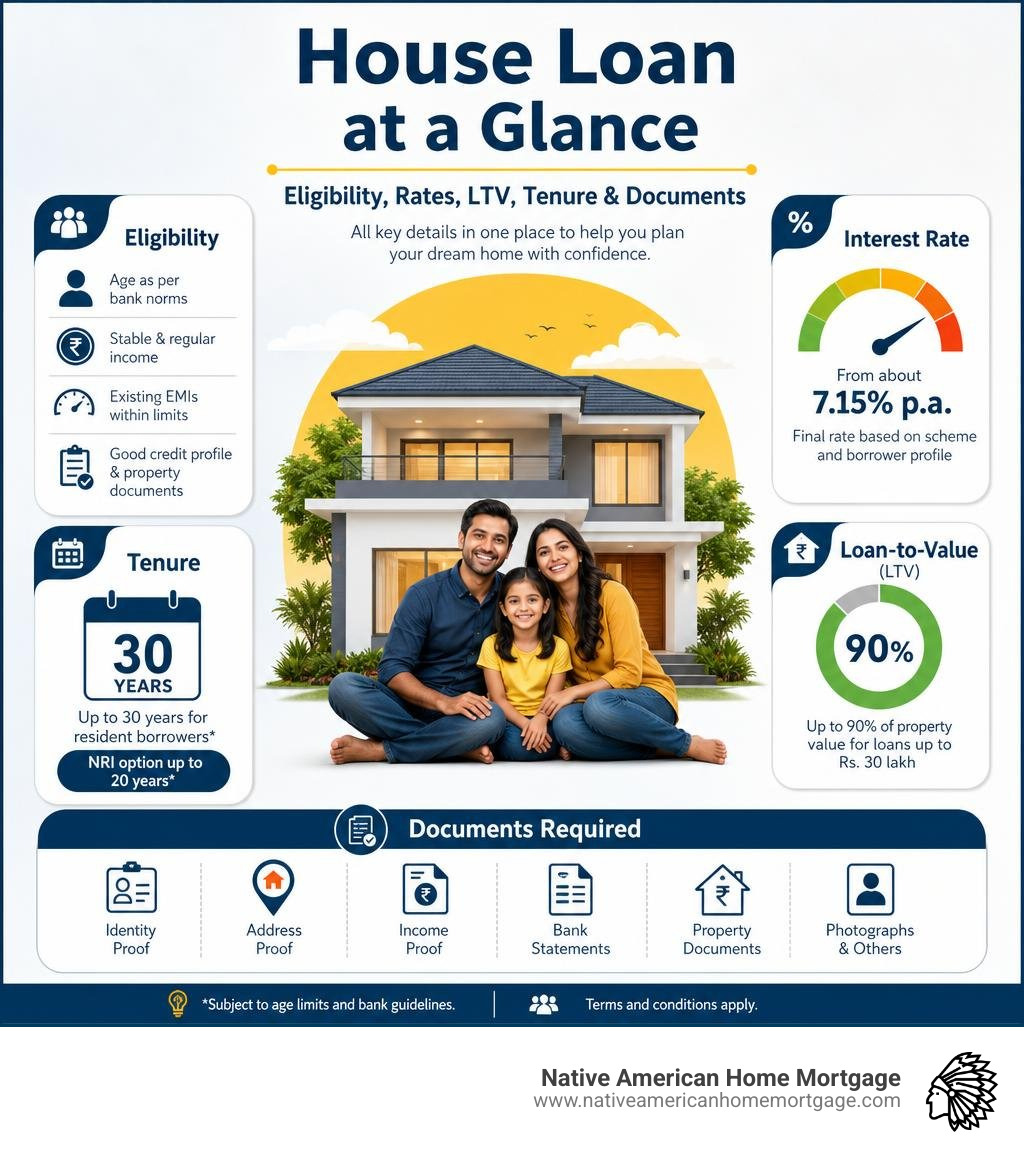
| Quick answer | Indian Bank home loan details |
|---|---|
| Starting floating rate | From about 7.15% p.a., with the final rate based on the scheme and borrower profile |
| Maximum tenure | Up to 30 years for resident borrowers, subject to age limits |
| Maximum funding | Up to 90% of property value for loans up to Rs. 30 lakh |
| Main eligibility checks | Age, stable income, existing EMIs, credit history, and property documents |
| NRI option | Available, generally with up to 20 years repayment tenure |
Indian Bank has several housing finance options, including standard home loans, overdraft-linked facilities, plot loans, improvement loans, and NRI home loans. The right option depends on what you are buying or building, how much you can pay each month, and whether the property and borrower meet the bank’s rules.
For borrowers who have felt overlooked by traditional lenders, the key is to understand the numbers before applying: the interest rate, loan-to-value limit, income rules, required take-home pay, and repayment period can all change the amount you qualify for.
I am Dale Gremillion, a Senior Loan Officer and Producing Branch Manager with more than 25 years in residential mortgage lending, including complex home financing for diverse borrower needs. While a house loan in Indian Bank follows Indian Bank’s own lending rules, my experience helps put the core questions around affordability, property financing, and long-term repayment into clear context.
House loan in indian bank terms explained:
Key Features and Schemes for a House Loan in Indian Bank
When you explore securing a house loan in Indian Bank, you will quickly discover that the bank does not take a one-size-fits-all approach. Instead, they structure their products around real-world homeownership scenarios. Whether you are buying your first urban apartment, self-constructing a bungalow on an ancestral plot, or transferring an existing mortgage from another institution, understanding these specialized products helps you pick the right fit. For a broader overview of how housing credit works across different markets, read All About Indian House Loan Options.
Specialized Loan Variants and Overdraft Options
Indian Bank offers several unique variants designed for specific financial situations:
- IB Home Loan: The flagship scheme designed for the purchase, construction, or takeover of a home or residential plot. It serves salaried individuals, self-employed professionals, and business owners.
- IB Home Advantage: An overdraft-linked home loan facility. This option allows you to deposit surplus cash into your loan account to offset interest calculations, giving you lower interest burdens while keeping liquidity accessible.
- IB Home Enrich: Formulated specifically for home repairs, renovation, furnishings, and structural extensions. This scheme is ideal when you want to modernize an existing residential property.
- IB Home Improve: Targeted at interior design, buying new fixtures, home equipment, and minor home modernization projects.
- NRI Home Loan and NRI Plot Loan: Customized solutions for Non-Resident Indians (NRIs) and Persons of Indian Origin (PIOs) looking to invest in residential property or plots in urban areas.
- IB Home Loan Plus: A top-up loan facility for existing borrowers who have maintained an excellent 12-month repayment track record, giving them extra liquidity for personal or domestic needs.
Interest Rates and LTV Ratios
Interest rates for an Indian Bank home loan are linked to external benchmarks (such as the Repo Rate). Floating interest rates typically start at around 7.15% p.a. to 7.40% p.a. depending on the borrower’s CIBIL credit score, income stability, and property type, ranging up to 9.55% p.a. or higher for niche plot and CRE categories. Fixed-rate options, where offered, generally range between 9.45% and 9.65% p.a.
The Loan-to-Value (LTV) ratio sets the maximum percentage of the property value that the bank is legally allowed to finance, leaving the remainder as your personal down payment or margin money.
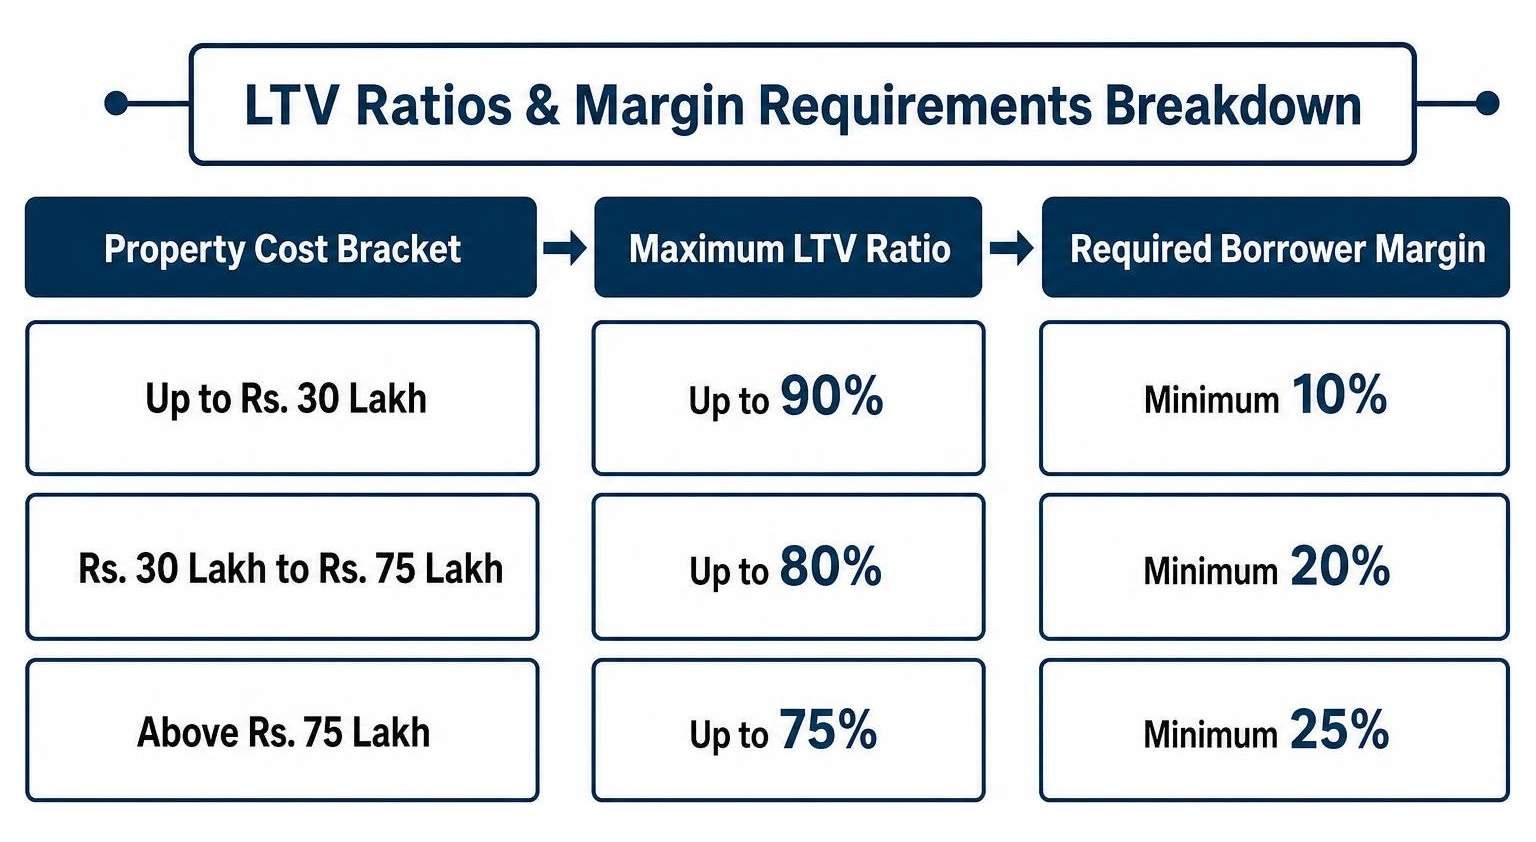
| Property Cost Bracket | Maximum LTV Ratio | Required Borrower Margin |
|---|---|---|
| Up to Rs. 30 Lakh | Up to 90% | Minimum 10% |
| Rs. 30 Lakh to Rs. 75 Lakh | Up to 80% | Minimum 20% |
| Above Rs. 75 Lakh | Up to 75% | Minimum 25% |
| Repairs and Renovation | Up to 70% (Project Cost) | Minimum 30% |
Eligibility Criteria and Financial Guidelines
Understanding loan approval starts with the core eligibility guidelines set by the bank. Lenders analyze age, continuous service history, self-employment turnover, and existing financial obligations to determine whether you can comfortably repay a long-term mortgage. To see how these compare with other major programs, check out our comprehensive Top Housing Loan Schemes Guide.

Eligibility and Income Rules for a House Loan in Indian Bank
Indian Bank enforces precise age, work history, and credit score standards:
- Age Limits: Resident individuals can apply starting at 18 years of age, with a maximum exit age of 70 years at loan maturity. For NRI applicants, the entry age is between 21 and 50 years, with a maximum exit age capped at 60 years.
- Salaried Employees: Must be regular employees of central or state governments, PSUs, educational institutions, or reputed private companies (rated BBB or higher). Private firm employees generally require a minimum of 2 years total work experience and 3 months of salary slips.
- Self-Employed and Business Owners: Loan amounts are based on the average gross income net of tax over the past 3 consecutive years, as verified through audited financial statements and Income Tax Returns (ITR).
- Loan Quantum Formula: For salaried workers, the loan capacity is calculated as up to 36 times the Gross Monthly Income or 60 times the Net Monthly Income, whichever generates a higher eligible limit.
- Credit Score Cutoff: While applicants with CIBIL scores of 650 or above are considered, maintaining a score of 750–800+ unlocks lower interest rates and smoother approvals.
- Gender-Based Concessions: Under specific programs like IB Home Enrich, women primary applicants or co-applicants can qualify for interest rate concessions ranging between 30 and 55 basis points.
Net Take Home Pay (NTHP) Requirements
To prevent financial distress, Indian Bank applies a mandatory Net Take Home Pay (NTHP) rule. This rule ensures you retain enough monthly income to cover basic living costs after all EMI obligations are deducted.
- Gross Annual Income up to Rs. 15 Lakh: Your net take-home salary after deducting existing EMIs and the proposed home loan EMI must not drop below 40% of your gross annual income.
- Gross Annual Income above Rs. 15 Lakh: You must maintain a absolute minimum Net Take Home Pay of at least Rs. 50,000 per month after all EMI deductions.
If your solo income falls short of this threshold, you can include your spouse, working children, or co-owners as co-applicants to pool income and qualify for higher funding.
Step-by-Step Application and Documentation Process
Applying for a housing loan requires clear step-by-step preparation. Having organized financial records, tax documents, and property deeds saves valuable time during verification. If you are exploring federally guaranteed options in North America alongside international housing programs, review the Section 184 Indian Home Loan Guarantee Program for specialized tribal housing details.

Document Checklist to Secure a House Loan in Indian Bank
To apply for a house loan in Indian Bank, prepare the following documents:
- KYC Documentation: Duly filled application form with signed photographs, PAN Card (mandatory), Aadhaar Card, Passport, or Voter ID.
- Salaried Income Proof: Latest 3 months salary slips, Form 16 for the past 2 to 3 years, and 6 months of active bank account statements showing salary credits.
- Self-Employed Income Proof: Computation of income, Profit & Loss statements, and Balance Sheets audited by a Chartered Accountant for the last 3 years, along with 12 months of business bank statements.
- NRI Specific Documents: Valid Passport, Visa copy/work permit, overseas address proof, latest 6 months salary slips, 6 months overseas bank account statements, NRE/NRO account statements, and POA (Power of Attorney) documentation attested by the Indian Embassy or Notary.
- Property Title Documents: Legal chain of title deeds (for 13 to 30 years), Encumbrance Certificate (EC) for a minimum of 13 years, approved building plan, property tax receipts, and an official builder allotment letter or NOC where applicable.
Processing Fees, Moratorium, and Repayment Tenure
- Processing Fees: Processing charges are typically 0.225% to 0.25% of the total loan amount, capped at a maximum of Rs. 20,000. Under promotional offers, processing fees may be fully waived.
- Prepayment Penalties: Per RBI regulations, there are NIL prepayment or foreclosure charges on floating-rate home loans for individual borrowers.
- Maximum Repayment Tenure: Resident borrowers can repay over up to 30 years, while NRI loans max out at 20 years. Repairs and home improvement loans have a 10-year maximum term.
- Moratorium / Holiday Period: For plot purchase and self-construction, Indian Bank provides a holiday period of up to 18 months from the initial disbursement or until construction completion. For under-construction apartments, moratorium periods can extend up to 36 months.
Frequently Asked Questions About Housing Loans
What is the maximum repayment tenure offered by Indian banks?
Resident individuals can secure home loans with repayment tenures of up to 30 years, provided the loan matures before the primary applicant turns 70 years old. For NRIs, the maximum repayment tenure is capped at 20 years (or up to 60 years of age). Home repair and modernization schemes carry a reduced maximum repayment term of 10 years.
How is the Net Take Home Pay calculated for home loan approval?
Net Take Home Pay (NTHP) is calculated by subtracting all current monthly debt payments and your proposed new home loan EMI from your total gross income. If your gross annual earnings are up to Rs. 15 lakh, your remaining net income must equal at least 40% of your gross earnings. If your annual income exceeds Rs. 15 lakh, you must retain at least Rs. 50,000 per month in net take-home pay.
Are there any prepayment charges on floating-rate home loans?
No. Indian Bank charges zero prepayment, partial prepayment, or full foreclosure fees on floating-rate home loans issued to individual borrowers. You can pay down your loan principal early whenever you have excess funds without incurring extra penalties.
Conclusion
Securing a house loan in Indian Bank offers lower floating interest rates, high LTV allowances up to 90%, flexible 30-year tenures, and distinct schemes designed for homebuyers, NRIs, and renovation projects. By keeping your credit score strong, gathering your tax records early, and meeting the bank’s Net Take Home Pay guidelines, you can navigate the loan application process with confidence.
At Native American Home Mortgage, we believe every family deserves clear, transparent financing advice tailored to their situation. Whether you are budgeting for a home purchase, comparing loan structures, or exploring long-term mortgage options across our served locations, evaluating your numbers early sets the stage for homeownership success. Explore our online tools, review your eligibility, and take the first step toward securing your ideal home loan today.