Understanding Native Community Capital Frameworks and Native CDFIs
Achieving true economic sovereignty in Indian Country requires financial infrastructure built specifically around tribal needs. For decades, traditional main-street banks struggled to navigate the unique legal, cultural, and land-tenure dynamics of tribal trust lands. Treasury-certified Native Community Development Financial Institutions (CDFIs) bridge this gap by providing tailored financial products, flexible underwriting, and deep community technical assistance.
To understand how native community capital operates, it helps to contrast traditional Western capital systems with Indigenous economic frameworks.
| Capital Framework Dimension | Western Extractive Model (Pipeline) | Indigenous Restorative Model (Waterway) |
|---|---|---|
| Primary Movement | Linear, pulling profit out of local areas | Circular, recirculating capital locally |
| Success Metric | Individual financial return and short-term yield | Collective community health and generational sustainability |
| Relationship to Land | Asset exploitation and resource extraction | Stewardship, placekeeping, and long-term care |
| Risk Assessment | Rigid credit scoring; land collateral requirements | Holistic credit evaluation, character, and community impact |
Transforming Capital Movement: The Waterway Model vs. Extractive Models
The “Pipeline” model of capitalism operates extrinsically: capital flows into a community, extracts wealth in the form of interest or profits, and pipes it away to outside institutions. This linear framework has historically left tribal communities undercapitalized and financially excluded.
In contrast, the “Waterway” model views economic flow as relational, circular, and restorative. Like natural water systems that nourish surrounding habitats, native community capital is meant to pool within tribal ecosystems. Wealth generated locally is reinvested into micro-grants, small business toolkits, affordable home mortgages, and local job creation. By focusing on capital circulation rather than extraction, Indigenous communities retain decision-making authority over their financial futures.
Native Community Capital Products for Small Business and Housing
Native CDFIs and community development partners offer financial services designed for both commercial and residential growth:
- Small Business Capital: Offering flexible working capital, business acquisition funding, equipment loans, and expansion financing for enrolled members of federally and state-recognized tribes operating on or off tribal lands.
- Mortgage Licensing and Trust Land Financing: Native financial institutions have secured licensed mortgage lender status, allowing them to directly originate and service loans on tribal trust lands where traditional lenders often hesitate to tread.
- Pre-Purchase Coaching: Integrating practical budgeting and credit restoration with specialized knowledge of Native home loan programs.
To explore the full spectrum of mortgage solutions tailored for tribal members, read A Complete Guide to Native American Home Loans and Buyer Programs.
Culturally Grounded Incubators and Indigenous Business Programs
Capital alone is rarely enough; it must be paired with culturally grounded technical assistance, physical infrastructure, and hardware access.
The Resilience Hub and Technical Training
In urban centers like Albuquerque, community organizations have pioneered urban architectural placekeeping by converting historic spaces into dynamic community hubs. An 8,000-square-foot facility serves as a “Community Nest,” bringing together tech infrastructure, ancestral wisdom, art, and entrepreneurship under one roof.
These hubs combat the digital divide directly by distributing essential hardware alongside technical education:
- Foundational Courses: Hands-on business and marketing courses covering digital research, competitive analysis, and financial forecasting.
- Business Tool Kits & Hardware: Reinvesting community funds directly into dedicated hardware, such as distributing over 540 Chromebooks valued at $188,710, paired with custom business tool kits totaling $55,696.
Programs and Measurable Community Impact
The long-term impact of pairing capital stipends with intensive training is evident across Indian Country:
- Native Entrepreneur In Residence (NEIR): Since 2014, 6-month intensive business accelerators have graduated 46 Native entrepreneurs, creating 265 local jobs.
- Direct Seed Funding: Over $1,488,495 in seed funding stipends has been awarded to participants completing essential business education courses, providing immediate liquidity for early-stage operations.
- Household Reach: Empowering over 2,000 Native households across tribal lands with digital tools and business guidance since 2018.
Empowering Native Women and Local Artisans
Native community initiatives center Indigenous women as key drivers of economic innovation:
- IndigiExchange First Fridays: Community market events offer cost-free vendor space to local Indigenous makers and culinary artists. By purchasing inventory upfront directly from creators, organizers ensure immediate liquid capital and guaranteed profits for artisans.
- Micro-Grants from Sales: Market revenues are continuously recycled into micro-grants for local startup businesses.
- Targeted Initiatives: Programs specifically designed for Indigenous women entrepreneurs offer multi-year leadership retreats, peer mentorship, and equity capital access.
Sovereign Wealth and High-Impact Enterprise Capital
Beyond individual business loans and mortgages, expanding native community capital requires macro-level strategies: building tribal sovereign wealth funds, deploying private equity, and leveraging federal financial programs.
Native Ventures and Sovereign Wealth Building
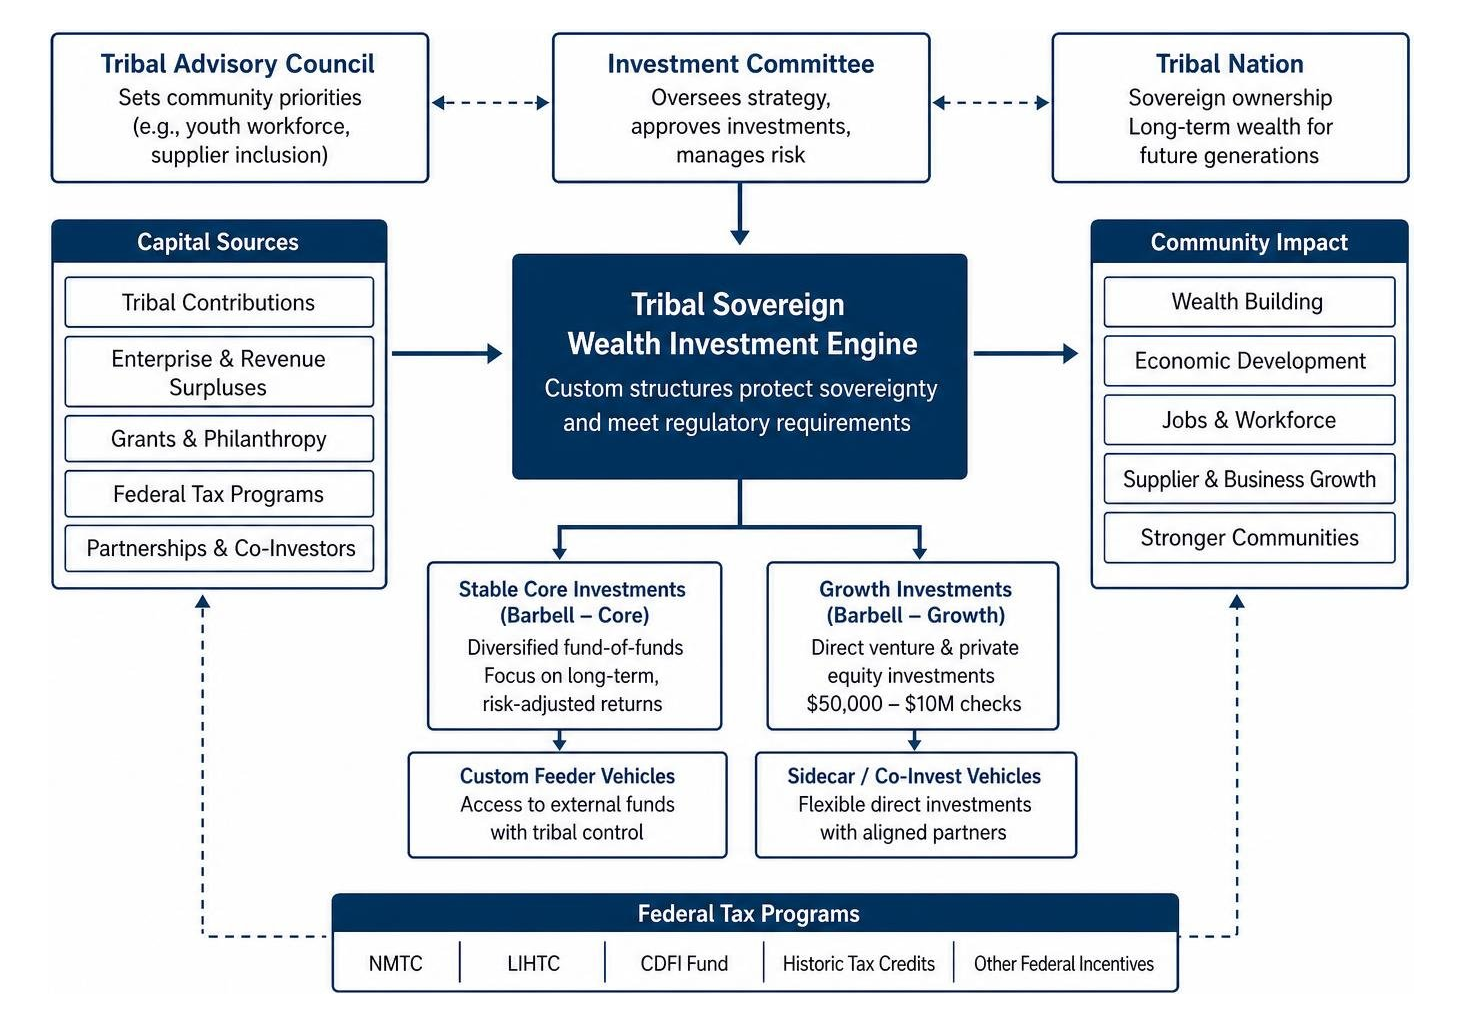
Tribal Nations are increasingly launching custom sovereign investment engines to build multi-generational wealth outside of traditional casino revenue. Using a balanced “barbell” investment strategy, tribes combine stable, diversified fund-of-funds investments with targeted direct checks into high-growth venture opportunities ($50,000 to $10 million).
To protect tribal sovereignty and satisfy regulatory requirements, these platforms use custom feeder vehicles and sidecar structures. A Tribal Advisory Council guides community impact priorities (like youth workforce development and supplier inclusion), while a dedicated Investment Committee executes rigorous financial management.
Leveraging NMTC and SSBCI Programs for Native Capital
Tribes and tribally owned financial institutions maximize federal programs to attract large-scale capital into reservation economies:
- New Markets Tax Credits (NMTC): Over $30 million in NMTC investments have been raised through tribally managed CDFIs to fund light manufacturing, technology hubs, and community facilities across Lower 48 tribes and Alaska Native villages.
- State Small Business Credit Initiative (SSBCI): Specialized consortia have secured allocations, including $7 million directed to small tribal groups, providing loan guarantees and direct co-investments.
- Triple Bottom Line: Projects prioritize a three-part metric—People (job creation and skill transfer), Profit (sustainable financial performance), and Planet (environmental stewardship aligned with cultural values).
Mortgage Assistance, Down Payment Grants, and Housing Loans
Housing security forms the bedrock of community stability. By pairing specialized mortgage products with homebuyer grant programs, Native families can navigate complex land structures and secure affordable homeownership.
Homeowner Assistance Funds and Down Payment Support
Federal grant allocations and native asset coalitions have funneled millions in targeted mortgage relief directly to eligible Native families:
- Navajo Homeowner Assistance Fund (NHAF): Programs have deployed $11.7 million in grant funding, delivering direct principal reduction payments to mortgage lenders. Grants are age-tiered—offering up to $100,000 for homeowners under 55 and up to $150,000 for those 55 and older who experienced qualifying hardships.
- Regional Asset Coalitions: Partnerships like the Oklahoma Native Assets Coalition (ONAC) leverage grant funding—including $1.05 million secured via Federal Home Loan Bank (FHLBank Topeka) programs—to provide down payment assistance, financial coaching, emergency savings, and Children’s Savings Accounts across Oklahoma.
Utilizing Native Community Capital Mechanisms for Home Loans
Navigating mortgage approval on tribal trust land requires specialized knowledge of federal lending options. The flagship program for Native borrowers is the HUD Section 184 Indian Home Loan Guarantee Program, created specifically to overcome the legal hurdles of financing homes on trust land.
Key mortgage options and capital strategies include:
- HUD Section 184 Loans: Feature low down payment requirements (as low as 2.25%), flexible underwriting, and standard market interest rates for eligible tribal members. Learn the fundamentals with What is a HUD 184 Loan? Your Ticket to Native Homeownership.
- Construction-to-Permanent Financing: Combining land preparation, utility hookups, and residential construction into a single closing to minimize fees. Read The Ultimate Guide to Construction to Permanent Loans to understand how this process works.
- Optimizing Approval Odds: Documenting income, working with Native-focused housing counselors, and utilizing down payment assistance grants can significantly boost qualification success. See our guide on Native American Mortgage Approval Odds and How to Improve Them.
For additional guidance on federal requirements, review the official HUD Section 184 Program Details.
Frequently Asked Questions
What is native community capital and what core services does it offer?
Native community capital refers to the ecosystem of Treasury-certified Native CDFIs, tribal housing authorities, loan funds, and non-profit partners providing specialized capital to Indian Country. Core services include small business working capital, direct mortgage lending on tribal trust lands, down payment grant administration, financial coaching, and sovereign wealth advisory.
How does the Waterway economic model differ from Western capitalism?
Traditional Western capitalism often functions as an extractive “Pipeline,” moving profit away from local communities to external investors. The Indigenous “Waterway” model is circular and restorative: capital is retained locally to nourish small businesses, housing, and social infrastructure, ensuring long-term community benefit.
How can Native entrepreneurs and homebuyers apply for capital programs?
Homebuyers and business owners can apply by contacting Native CDFIs, regional asset coalitions, or specialized mortgage lenders. Applicants complete pre-qualification forms, verify tribal enrollment, and participate in homebuyer or financial education courses to unlock direct grants, low-interest small business loans, or HUD 184 mortgage financing.
Conclusion
Building long-term wealth in Indian Country requires financial tools that align with tribal sovereignty, trust land realities, and community values. Native community capital bridges historical funding gaps by turning linear, extractive lending into a circular, restorative ecosystem that keeps capital working for Native families and future generations.
Whether you are seeking small business capital, down payment assistance grants, or a single-close construction loan on trust land, having experienced guidance is essential. Explore your mortgage options and take the next step toward homeownership by visiting Native American Home Mortgage.