What is the CDFI Fund and How Does It Capitalize Underserved Communities?
The Community Development Financial Institutions Fund—commonly known as the CDFI Fund—operates as a specialized bureau within the U.S. Department of the Treasury. Its fundamental mission is to generate economic growth and expand opportunity in distressed urban, rural, and Native American communities across the nation.
Rather than acting as a direct lender to individual consumers or small businesses, the CDFI Fund utilizes a market-based model. It injects targeted federal seed capital, tax credits, and financial guarantees directly into mission-driven financial institutions. These specialized institutions then leverage those federal dollars alongside private capital to deliver affordable loans, investments, and financial services to underserved markets. To learn more about the broader framework of the agency, you can explore About Us | Community Development Financial Institutions Fund.
Origins, Mission, and Statutory Role of the CDFI Fund
The agency was formally established under the bipartisan Riegle Community Development and Regulatory Improvement Act of 1994. Prior to its creation, mainstream commercial banks and traditional credit markets often overlooked economically distressed geographic areas, viewing low-income populations and unbanked regions through a lens of unmanageable financial risk.
The statutory mandate of the CDFI Fund was created to change that dynamic. By providing competitive monetary grants and financial incentives to specialized local lenders, the federal government helps bridge the gap between traditional private capital markets and capital-starved communities. The Fund operates under the conviction that access to fair, affordable credit and financial coaching is essential for building wealth, launching local businesses, and developing quality affordable housing.
CDFI vs. CDE Certification: Understanding the Key Differences
A common point of confusion for local leaders, business owners, and housing developers is the distinction between a Certified Community Development Financial Institution (CDFI) and a Certified Community Development Entity (CDE). While both designations are administered by the CDFI Fund, they serve different primary funding channels and operational functions.
A certified CDFI is a financial institution whose primary mission is promoting community development. CDFIs provide direct lending, financial products, and development services to low-income target markets. On the other hand, a CDE is a domestic corporation or partnership that serves as an intermediary vehicle specifically designed to hold equity investments and issue tax credits under the New Markets Tax Credit (NMTC) Program. All certified CDFIs automatically qualify as CDEs, but a CDE is not automatically a certified CDFI.
| Organizational Criteria | Community Development Financial Institution (CDFI) | Community Development Entity (CDE) |
|---|---|---|
| Primary Focus | Direct financial products, community lending, and financial counseling. | Intermediary investment management and tax credit allocation. |
| Primary Federal Program | CDFI Program (Financial & Technical Assistance awards). | New Markets Tax Credit (NMTC) Program. |
| Target Market Accountability | Must maintain accountability to low-income or underserved target markets. | Must demonstrate accountability to low-income communities (LICs). |
| Eligible Entities | Banks, credit unions, non-profit loan funds, and venture capital funds. | Corporations, partnerships, and financial intermediaries. |
| Automatic Dual Status | Yes—certified CDFIs are automatically recognized as CDEs. | No—CDE certification does not confer full CDFI status. |
Overview of Primary Programs Administered by the U.S. Treasury
To fulfill its legislative vision, the CDFI Fund manages a diverse portfolio of grant, equity, tax credit, and debt guarantee initiatives. These core programs address different aspects of economic distress, ranging from micro-enterprise financing and food access to large-scale infrastructure projects.
CDFI Program, Financial Assistance, and Technical Assistance
The flagship initiative of the agency is the CDFI Program. It equips certified institutions with the capital required to build their internal capacity and expand their local lending footprints. For detailed guidelines on award structures and funding cycles, visit the official CDFI Program | Community Development Financial Institutions Fund page.
The program delivers funding through two primary avenues:
- Financial Assistance (FA) Awards: Provided directly to certified CDFIs in the form of grants, loans, equity investments, or deposits. FA awards require a strict dollar-for-dollar non-federal matching funds requirement, ensuring that federal investments pair directly with private capital. In FY 2024 alone, CDFI Program awardees financed over 109,000 local businesses, funded more than 45,000 affordable housing units, and originated over $24 billion in loans and investments.
- Technical Assistance (TA) Awards: Offered as direct grants to both certified CDFIs and emerging institutions. TA awards do not require matching funds and are designated for internal capacity building—such as upgrading technology, acquiring professional training, or hiring expert staff—to help emerging lenders achieve full certification within three years.
The New Markets Tax Credit (NMTC) Program and Rural Community Incentives
Established by Congress under the Community Renewal Tax Relief Act of 2000, the New Markets Tax Credit Program is one of the most powerful economic development tools in the federal government’s arsenal. To date, the program has allocated over $81 billion in tax credit authority to certified CDEs, leveraging more than $135 billion in total capital investments into high-poverty communities through late 2023.
The NMTC program incentivizes private real estate developers and institutional investors by offering a 39% federal tax credit—spread over seven years—in exchange for equity investments made in qualified low-income communities. These tax-credit-driven investments have created more than 1.2 million jobs nationwide at a federal tax cost under $20,000 per job.
Furthermore, recent program reforms have emphasized rural equity. Treasury allocations now incorporate a explicit target that reflects a 20 percent increase in investments directed specifically toward rural and non-metropolitan communities, ensuring that small towns receive their fair share of capital for domestic manufacturing, regional healthcare facilities, and educational centers.
Affordable Housing and Capital Infrastructure: CMF, BEA, and Bond Guarantees
Beyond core lending and tax credit initiatives, the CDFI Fund oversees three specialized financial tools designed to build infrastructure and stimulate private investment:
- Capital Magnet Fund (CMF): Funded through statutory assessments on Fannie Mae and Freddie Mac, CMF awards competitive grants to certified CDFIs and non-profit housing developers. Through late 2024, CMF funding applied to fully completed housing projects generated $17.6 billion in total project capital from an initial $556.6 million in grant awards—a remarkable leverage ratio of nearly $30 in private and public project funding for every $1 of federal award money. This has enabled the creation of over 83,000 affordable homes nationwide.
- Bank Enterprise Award (BEA) Program: The BEA Program incentivizes traditional FDIC-insured depository institutions to increase their monetary support of certified CDFIs and expand their direct commercial lending and financial services within distressed target areas. Since its inception in 1994, the program has awarded over $638 million, encouraging traditional banks to partner directly with community-focused lenders.
- CDFI Bond Guarantee Program: Designed for large-scale economic development, this program provides full federal guarantees on long-term bonds issued by qualified financial structures. To date, the Treasury has guaranteed nearly $3 billion in bonds, giving CDFIs access to low-cost, long-term capital for large infrastructure projects, charter schools, health clinics, and multi-family housing complexes.
Becoming a Certified CDFI: Seven Core Requirements and Industry Structure
As of late 2024, there were 1,426 Treasury-certified CDFIs operating across all 50 states, the District of Columbia, Guam, and Puerto Rico. Collectively, the CDFI industry manages over $436 billion in total financial assets, maintaining net industry equity of $45.2 billion.

The Seven Requirements for Official CDFI Certification
To earn official certification from the CDFI Fund, an applicant organization must satisfy seven precise statutory tests:
- Legal Entity: The organization must be a formally recognized legal entity (such as a corporation, non-profit loan fund, or cooperative) at the time of application.
- Primary Mission: The entity must demonstrate that its primary mission is promoting economic development and community revitalization.
- Target Market: The institution must direct at least 60% of its total financial products and services toward eligible target markets, such as investment areas or targeted low-income populations.
- Financial Products and Services: Providing financial products (such as loans, micro-credits, equity investments, or guarantees) must be the entity’s predominant business activity.
- Development Services: The organization must provide essential financial development services alongside its lending activities, such as financial literacy coaching, business technical assistance, or homebuyer education.
- Target Market Accountability: The institution must maintain direct governance or advisory accountability to its chosen target market through board representation or community advisory councils.
- Non-Governmental Entity: The applicant must operate independently as a non-governmental entity and cannot be controlled by a federal, state, or municipal government agency.
Industry Snapshot: Banks, Credit Unions, Loan Funds, and Native Initiatives
The CDFI ecosystem consists of four main institutional models, each addressing specific local capital needs:
- Community Development Loan Funds (39% of certified CDFIs): Typically non-profit entities that provide micro-loans, small business financing, and real estate development capital.
- Community Development Credit Unions (35% of certified CDFIs): Member-owned financial cooperatives that provide affordable consumer loans, residential mortgages, and deposit accounts to low-income communities. Credit unions account for 64.6% ($281.5 billion) of total CDFI industry assets.
- Community Development Banks and Thrifts (14% of certified CDFIs): For-profit, FDIC-insured financial institutions that channel commercial credit and checking services into under-resourced neighborhoods. Banks hold 26.0% ($113.2 billion) of industry assets.
- Community Development Venture Capital Funds (1% of certified CDFIs): Entities providing equity capital and operational expertise to high-growth, job-creating businesses in distressed markets.
A crucial pillar within this ecosystem is the Native Initiatives (NACA Program). Native CDFIs specialize in serving Native American, Alaska Native, and Native Hawaiian communities, where traditional commercial bank branches are frequently absent. Through the NACA Program, the CDFI Fund has awarded over $289.8 million in technical and financial assistance.
This dedicated funding has fueled dramatic growth: the number of certified Native CDFIs expanded from just 14 institutions in 2001 to 64 certified lenders operating today. For an in-depth look at how these entities drive sovereignty and economic mobility, read our guide on Unlocking Financial Growth in Indian Country Through Native Loans and Grants.
Recent Policy Reforms, Status, and Navigating Services
Recent Policy Changes, Revised Reporting, and Current Operating Status
To ensure high standards of transparency and community accountability, the Treasury implemented major structural updates in late 2023 and 2024. The agency released a revised CDFI Certification Application alongside updated Annual Certification and Data Collection Reports (ACR) and Transaction Level Reports (TLR). These modernized reporting standards require certified lenders to provide detailed loan-level reporting via the Awards Management Information System (AMIS) to confirm that their capital continues to reach designated low-income populations.
In early 2025, public debate surrounding federal agency spending included an executive order directing a review and proposed restructuring of various federal grant programs. However, because the CDFI Fund was created by explicit congressional statute under the Riegle Act of 1994, its program mandates, existing funding cycles, and statutory grant obligations remain intact. Certified CDFIs continue operating across the nation, maintaining active lending programs and receiving federal grant reimbursements as authorized by Congress.
How Local Businesses and Borrowers Can Access CDFI Fund Resources
If you are an individual homeowner, small business owner, or real estate developer seeking financing, you do not apply directly to the federal Treasury. Instead, you connect directly with certified local institutions in your area.
To locate certified lenders, access the tools provided at the official portal for Home | Community Development Financial Institutions Fund. Users can utilize the public Awards Database search tool to filter active awardees by program and state.
Furthermore, economic developers and business owners can utilize the Treasury’s online CDFI Public Viewer mapping tool (integrated with the Community Information Mapping System, or CIMS) to verify whether a specific property address falls within a qualified CDFI Investment Area:
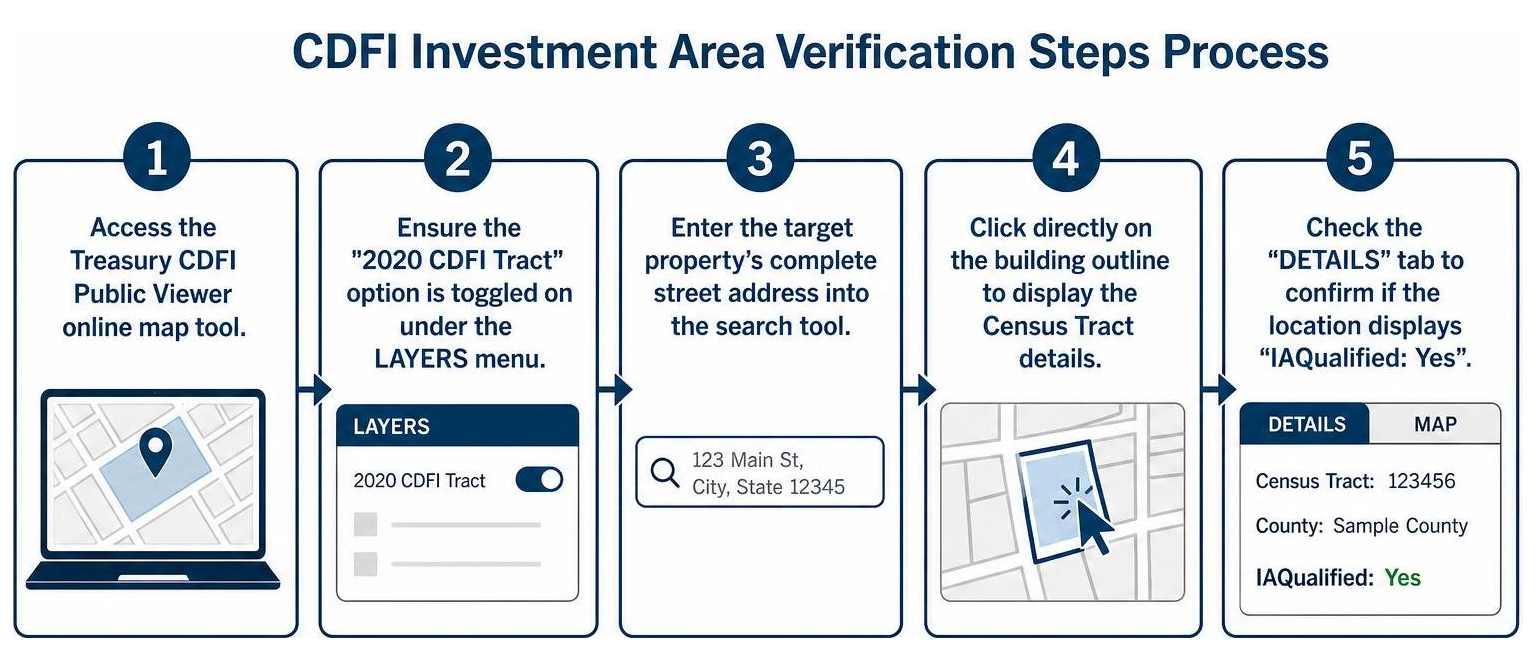
- Access the Treasury CDFI Public Viewer online map tool.
- Ensure the “2020 CDFI Tract” option is toggled on under the LAYERS menu.
- Enter the target property’s complete street address into the search tool.
- Click directly on the building outline to display the Census Tract details.
- Check the “DETAILS” tab to confirm if the location displays “IAQualified: Yes”.
Once connected with a local lender, borrowers gain access to what the industry calls “Capital Plus”—a combination of fair, low-cost financing paired with essential technical assistance, small business coaching, and homebuyer preparation. For additional pathways to housing resources, read our comprehensive overview on How to Find Native American Housing Programs and Financial Support.
Frequently Asked Questions About the CDFI Fund
What is the historical economic impact of the CDFI Fund since 1994?
Since its creation in 1994, the CDFI Fund has delivered extraordinary returns on federal investment:
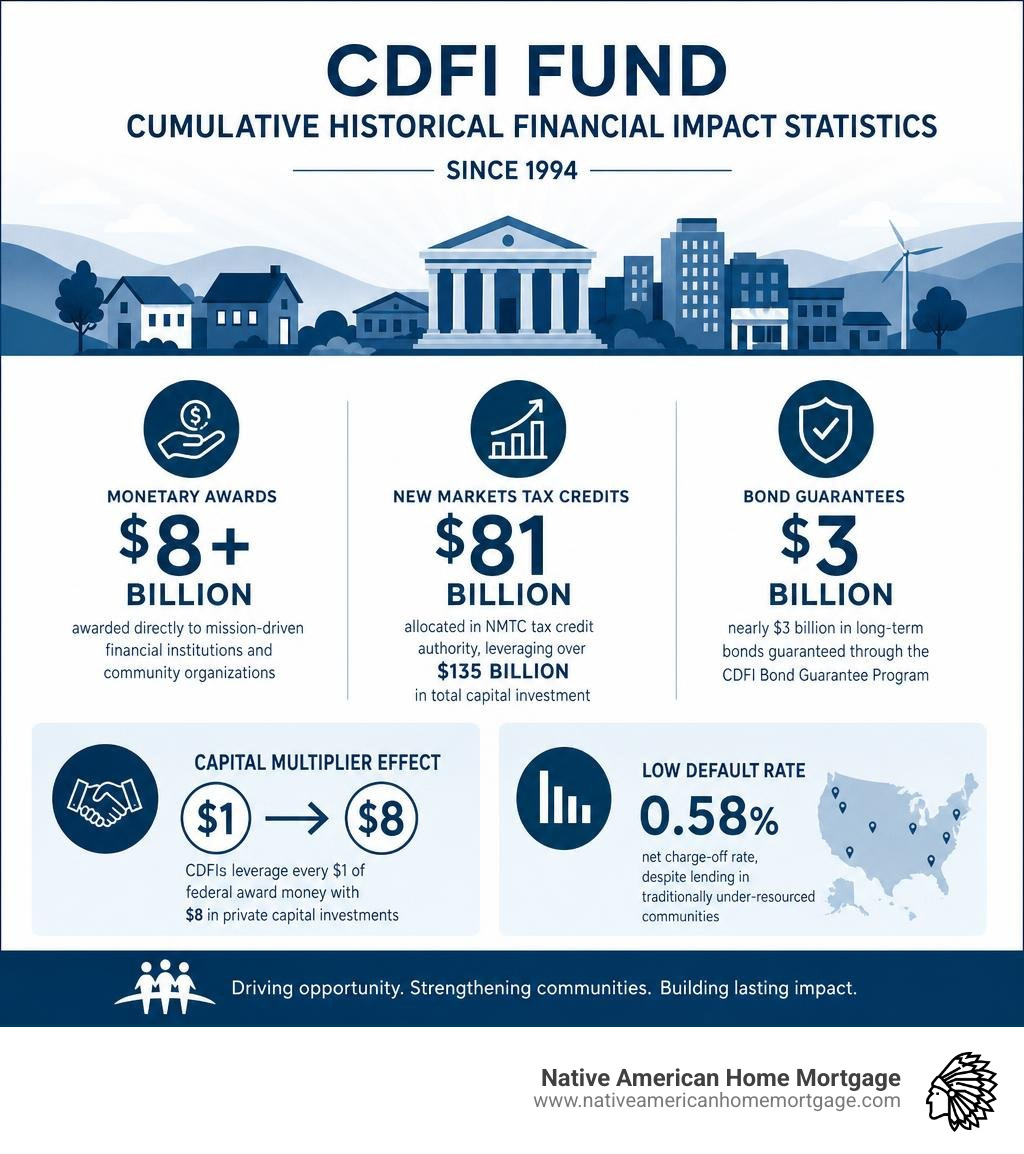
- Monetary Awards: Over $8 billion awarded directly to mission-driven financial institutions and community organizations.
- New Markets Tax Credits: $81 billion allocated in NMTC tax credit authority, leveraging over $135 billion in total capital investment.
- Bond Guarantees: Nearly $3 billion in long-term bonds guaranteed through the CDFI Bond Guarantee Program.
- Capital Multiplier Effect: CDFIs leverage every $1 of federal award money with $8 in private capital investments.
- Low Default Rate: Despite lending in traditionally under-resourced communities, CDFIs maintain an exceptionally low net charge-off rate of just 0.58%.
- Targeted Demographics: Nationwide, 68% of CDFI clients are people of color, 82% are low-income, 52% are women, and 25% reside in rural communities.
How does the CDFI Fund interact with Native American housing programs?
The CDFI Fund works alongside federal housing programs to expand homeownership opportunities in Indian Country. While Native CDFIs provide down payment assistance, financial literacy coaching, and secondary mortgage financing through the NACA Program, home buyers frequently pair these local resources with specialized federal loan programs.
For instance, borrowers can combine Native CDFI assistance with the HUD Section 184 program to secure low-down-payment home loans on trust or fee-simple land. To learn more about HUD mortgage options, visit the official page for the Section 184 Indian Home Loan Guarantee Program – HUD. For step-by-step guidance on securing housing grants, check out our guide on How to Secure Native American Housing Grants This Year.
What is the difference between Financial Assistance and Technical Assistance awards?
Financial Assistance (FA) awards provide direct equity, capital reserves, or loanable funds to certified CDFIs that can demonstrate a matching dollar-for-dollar commitment from non-federal private sources.
Technical Assistance (TA) awards, by contrast, are capacity-building grants available to both certified CDFIs and emerging entities. TA awards require no matching funds and can be used to purchase software, train staff, acquire equipment, or hire consultants to help an emerging institution build its lending platform.
Conclusion
The CDFI Fund stands as one of the most effective examples of public-private collaboration in modern economic policy. By utilizing federal seed money to leverage substantial private equity, the agency empowers local banks, credit unions, and loan funds to deliver capital where traditional finance falls short. Whether funding affordable housing construction, expanding rural health clinics, or supporting small businesses, CDFIs transform distressed neighborhoods into thriving local economies.
At Native American Home Mortgage, we share a deep commitment to expanding homeownership and economic opportunity in underserved and Tribal communities. By pairing mission-driven lending insights with specialized mortgage tools like HUD 184 and FHA financing, we help families and local partners build lasting wealth. Explore our resources today to discover how specialized home financing options can turn your community development goals into reality.