Why the Native American Home Purchase Process Is Different — and How to Master It
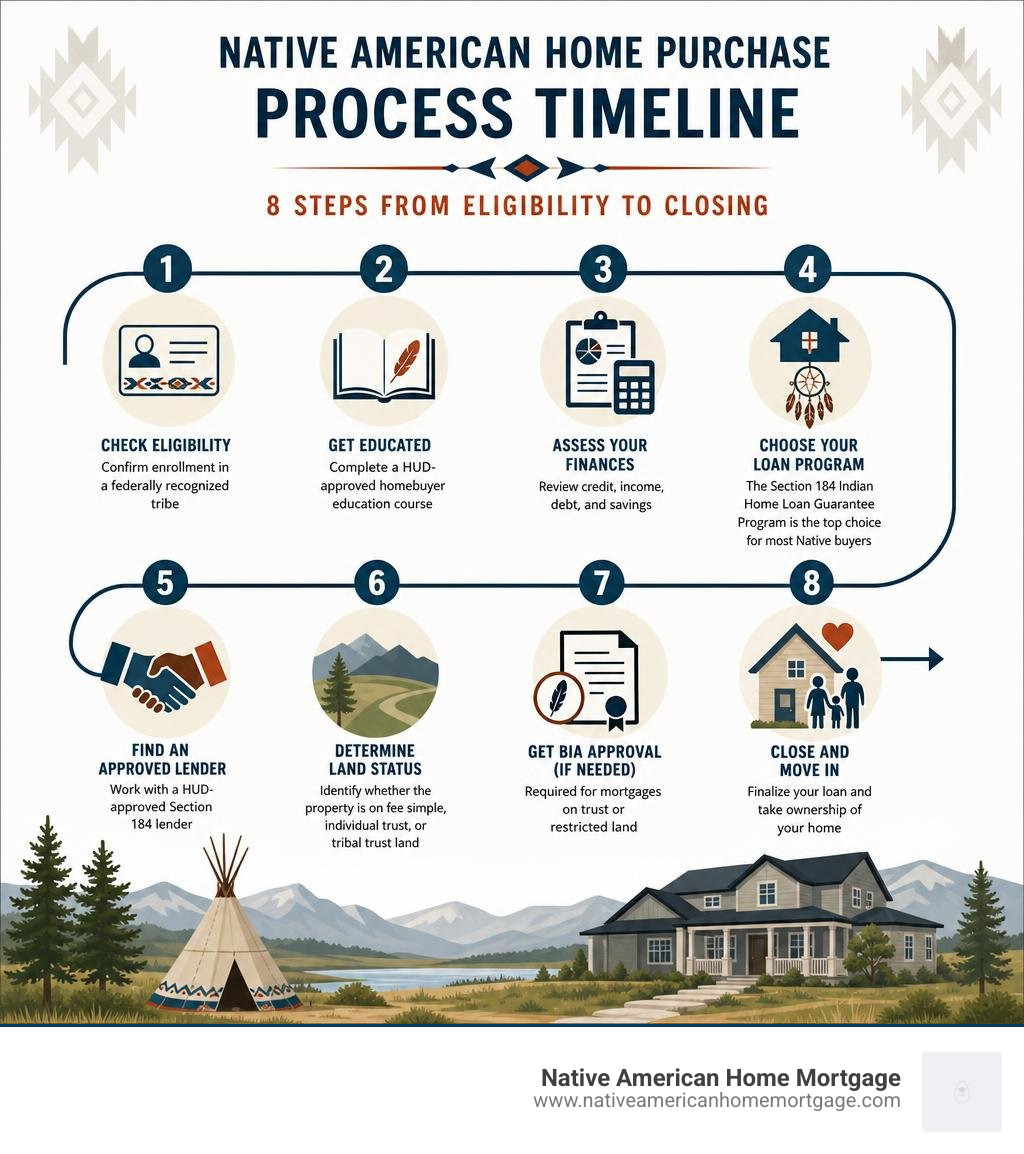
The Native American home purchase process comes with a unique set of rules, programs, and land-related complexities that most conventional lenders simply don’t understand. Here’s a quick overview of how it works:
- Check eligibility – Confirm enrollment in a federally recognized tribe
- Get educated – Complete a HUD-approved homebuyer education course
- Assess your finances – Review credit, income, debt, and savings
- Choose your loan program – The Section 184 Indian Home Loan Guarantee Program is the top choice for most Native buyers
- Find an approved lender – Work with a HUD-approved Section 184 lender
- Determine land status – Identify whether the property is on fee simple, individual trust, or tribal trust land
- Get BIA approval (if needed) – Required for mortgages on trust or restricted land
- Close and move in – Finalize your loan and take ownership of your home
The gap in homeownership between Native Americans and the broader population tells a stark story. Today, only about 56% of Native Americans own their homes — roughly 15 percentage points below the national average. On tribal lands, nearly 16% of households live in overcrowded conditions, compared to just 2.2% nationally. These aren’t just statistics. They reflect real families who want to own homes — in fact, about 75% of Native households in tribal areas say they do — but face barriers that conventional lenders aren’t equipped to handle.
The good news? There are powerful federal programs, tribal resources, and specialized lenders built specifically to bridge this gap.
I’m Dale Gremillion (NMLS #210325), a Senior Loan Officer with over 20 years of mortgage experience and a deep specialization in the Native American home purchase process, particularly through the HUD Section 184 Indian Home Loan Guarantee Program. I’ve guided countless tribal members through the unique legal, financial, and land-related hurdles of this process — and this guide walks you through everything I know.
Understanding the Section 184 Indian Home Loan Guarantee Program
When discussing the Native American home purchase process, the conversation must begin with the Section 184 Indian Home Loan Guarantee Program. Established by Congress in 1992, this program was designed to address the lack of mortgage capital in Indian Country.
The program is managed by the Office of Loan Guarantee within HUD’s Office of Native American Programs. Because traditional mortgages require land to be used as collateral, lending on sovereign tribal trust land was historically nearly impossible. HUD solved this by offering a 100% loan guarantee to participating lenders. If a borrower defaults, HUD steps in to protect the lender from foreclosure loss. This complete elimination of lender risk has unlocked billions of dollars in private capital for Native families.
To learn more about how this serves as your entry point, read our comprehensive overview on What is a HUD 184 Loan? Your Ticket to Native Homeownership.
Eligibility Criteria and Tribal Enrollment Verification
Who can take advantage of this game-changing program? Eligibility is open to:
- Individual American Indians or Alaska Natives who are enrolled members of a federally recognized tribe.
- Federally recognized Indian tribes.
- Tribally Designated Housing Entities (TDHEs).
- Indian Housing Authorities (IHAs).
For individual buyers, verifying your tribal enrollment is the first administrative step. You must provide a copy of your tribal enrollment card or a Certificate of Degree of Indian Blood (CDIB) issued by your tribe or the Bureau of Indian Affairs (BIA). For detailed guidelines on what documents are required, check out The Complete Guide to Section 184 Loan Qualifications and Guidelines.
Key Benefits: Down Payments, Interest Rates, and Underwriting
The Section 184 program is incredibly borrower-friendly, offering some of the most competitive terms in the entire mortgage industry:
- Low Down Payment: You only need a 1.25% down payment on loans under $50,000, and just 2.25% on loans over $50,000.
- No Annual Guarantee Fees: For all loans closed on or after July 1, 2023, HUD completely eliminated the annual loan guarantee fee. You only pay a one-time 1% upfront guarantee fee, which can be financed directly into the loan.
- Fair Interest Rates: Unlike conventional loans where your credit score dictates your rate, Section 184 interest rates are based on prevailing market rates, not your credit score.
- Manual Underwriting: Instead of relying on rigid automated underwriting algorithms that often penalize non-traditional credit histories, Section 184 underwriters manually review every file, allowing for flexible, common-sense evaluations of your creditworthiness.
For an in-depth breakdown of how these perks compare to standard loans, see Unlocking the Door: How HUD 184 Makes Home Buying a Breeze.
Eligible Uses and Geographic Areas for Section 184
The Section 184 loan is highly versatile. It can be used for:
- Purchasing an existing single-family home (1 to 4 units).
- Constructing a new home from the ground up.
- Rehabilitating an existing home.
- A combination of purchase and rehabilitation.
- Refinancing an existing mortgage (fixed-rate only; adjustable-rate mortgages are strictly prohibited).
Importantly, Section 184 loans are not restricted to reservation boundaries. They can be used on fee simple land in designated, HUD-approved counties. In our primary Southwest service areas of Arizona, New Mexico, Utah, and Colorado, a significant portion of counties are fully approved for off-reservation Section 184 lending. To learn more about geographic rules, read No Reservation Required to Nail Your HUD 184 Loan Application.
Step-by-Step Guide to the Native American Home Purchase Process
Buying a home is a journey, and having a clear roadmap is essential to navigating the paperwork, agencies, and timelines without losing your peace of mind.

To help you stay on track, we have created a step-by-step roadmap in How to Apply for HUD 184 Loan Benefits Without Getting Lost in the Bureaucracy. Let’s explore the critical preparatory phases.
Preparing Your Finances for the Native American Home Purchase Process
Before you apply, you should conduct a thorough self-assessment of your financial health. While Section 184 underwriting is flexible, you must still prove you have stable income and the ability to repay the debt.
- Employment History: Lenders typically look for a stable two-year employment history.
- Debt-to-Income (DTI) Ratio: Your monthly debt obligations (including your future mortgage payment) should ideally not exceed 41% to 45% of your gross monthly income, though manual underwriting can allow for higher ratios if compensating factors exist.
- Credit Check: Order your credit reports and check for errors. While there is no strict minimum credit score mandated by HUD, individual lenders may have their own overlays, and a cleaner report makes manual approval much smoother.
- Avoid New Debt: A golden rule of the Native American home purchase process is to freeze all new credit inquiries. Do not buy a new car, open new credit cards, or co-sign loans during this period.
For more tips on setting yourself up for approval, read our guide on Native American Home Loan Approval.
Homebuyer Education and Counseling Resources
Education is the absolute cornerstone of successful homeownership. Completing a certified homebuyer education class is highly recommended (and often required, especially if you are utilizing down payment assistance).
These classes cover budgeting, understanding mortgage terms, and maintaining your home. You can find free or low-cost certified homebuyer counseling resources directly through the Borrowers Section 184 Loan Resources | HUD.gov / U.S. Department of Housing and Urban Development (HUD) portal.
Finding and Working with a HUD-Approved Lender
You cannot get a Section 184 loan from just any bank. You must work with a lender specifically approved by HUD to originate and service these specialized loans. Working with an experienced professional ensures that your file is processed correctly, avoiding common pitfalls with land status and BIA approvals.
To understand how to choose the right partner, check out Demystifying Section 184: Your Path to Affordable Tribal Homeownership.
Navigating Land Status: Trust Land vs. Fee Simple Land
One of the most complex aspects of the Native American home purchase process is the legal status of the land itself. In Indian Country, land is generally categorized into three types, each requiring a completely different legal approach for securing a mortgage.
| Land Status Type | Legal Title Holder | Can it be Mortgaged Directly? | Key Requirement for Lending |
|---|---|---|---|
| Fee Simple Land | Individual Owner | Yes | Standard title insurance and mortgage liens. |
| Individual Trust Land (Allotted) | Federal Government (in trust for individual) | Yes (with BIA approval) | Requires BIA approval and a Title Status Report (TSR). |
| Tribal Trust Land | Federal Government (in trust for the Tribe) | No | Requires a long-term residential leasehold mortgage. |
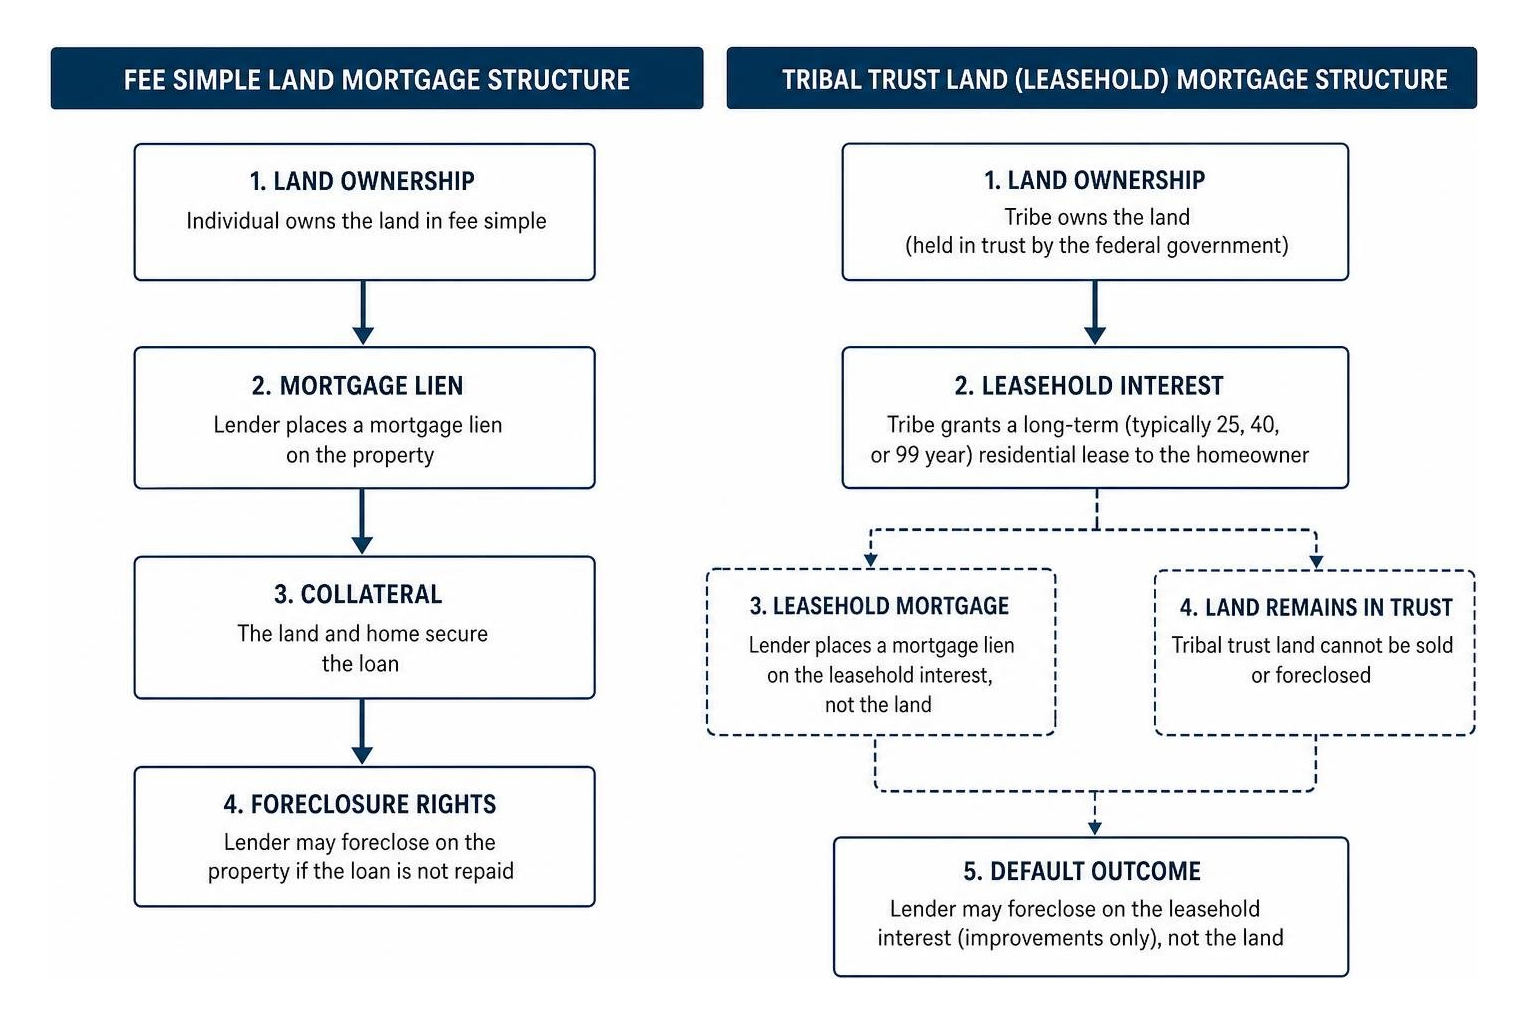
Understanding these structural differences is key to preventing major delays during your home search. For an exhaustive, regulatory breakdown of these concepts, you can consult the Guide to Mortgage Lending in Indian Country .
Navigating the Native American Home Purchase Process on Trust Land
Because tribal trust land belongs to the tribe collectively and is held in trust by the federal government, it cannot be sold, subdivided, or directly mortgaged. To bypass this barrier and protect sovereign land from leaving tribal hands, lenders use a leasehold interest.
Under this system, the tribe leases a specific parcel of land to the individual homebuyer for a long-term period (typically 50 years under NAHASDA guidelines). The homebuyer then mortgages the leasehold interest rather than the land itself. If a foreclosure were to occur, the land remains in tribal trust, and the leasehold interest is transferred to another eligible tribal member or the housing authority. To see how this legal framework keeps reservation lending secure, read FHA and Section 184: Your Guide to the Indian Loan Guarantee Program.
The Bureau of Indian Affairs (BIA) Approval Process
If you are leasing tribal trust land or mortgaging individual trust land, the Bureau of Indian Affairs (BIA) must be involved. The BIA is responsible for tracking ownership and land status through its regional offices.
To secure your loan, the lender must obtain a Title Status Report (TSR) from the BIA. The TSR acts as the tribal equivalent of a title commitment, proving that the land is clear of competing liens and that the leasehold interest is legally valid. Because the BIA must manually process and approve these leasehold mortgages, this step can introduce administrative bottlenecks that require close communication between your lender, tribal housing staff, and the local BIA agency office.
Why the Section 184 Program is the Premier Choice for Native Buyers
The Section 184 program remains the undisputed gold standard for Native homebuyers, outperforming conventional, FHA, and USDA loans on multiple fronts. For a detailed comparison of all tribal housing programs, review All About Indian House Loan Options.
Lower Upfront and Ongoing Costs
With conventional loans, if you put down less than 20%, you are saddled with Private Mortgage Insurance (PMI), which can add hundreds of dollars to your monthly payment. FHA loans also carry hefty upfront and annual mortgage insurance premiums.
The Section 184 program completely eliminates annual mortgage insurance fees for loans closed on or after July 1, 2023. Combined with down payment requirements of just 1.25% to 2.25%, the upfront and monthly savings are immense.
Flexible Underwriting Tailored to Tribal Communities
Many Native Americans living in tribal communities have non-traditional credit profiles or unique income structures, such as tribal per-diem distributions, seasonal work, or self-employment. Traditional automated underwriting systems often flag these profiles as high-risk.
Section 184’s manual underwriting guidelines allow real human beings to analyze your application. We look at the big picture, acknowledging stable tribal income sources and non-traditional credit histories (like consistent rental, utility, or cell phone payment histories) to help you qualify.
Down Payment Assistance and Tribal Housing Initiatives
Even with low down payment requirements, coming up with cash for a down payment and closing costs can be a challenge. Fortunately, there are many programs designed to help Native buyers secure grants and second mortgages. You can learn more about finding these funds in How to Secure Native American Housing Grants This Year.
State and Local Down Payment Assistance Programs
Across the country, there are dozens of homebuyer assistance programs specifically designed to support Native American buyers, offering financial aid ranging from $2,125 to $90,000. Many of these programs are structured as forgivable second mortgages, meaning you do not have to repay the money as long as you live in the home for a specified number of years.
In our primary service areas of Arizona, New Mexico, Utah, and Colorado, state housing finance agencies and local tribal housing authorities offer specialized grants. Many of these programs are highly flexible, with some requiring no income limits at all, while others cater to those earning between 80% and 120% of the Area Median Income (AMI).
Federal Home Loan Bank (FHLB) and Affordable Housing Programs
The Federal Home Loan Bank (FHLB) system, including FHLB Des Moines (which services much of our Western region), provides substantial funding for Native housing initiatives. Through its Affordable Housing Program (AHP), the FHLB partners with local lenders to provide matching grants to low- and moderate-income Native homebuyers.
These programs are vital tools for building collective wealth on reservations. To understand how tribal leadership leverages these institutional resources, see the Tribal Leaders Handbook on Homeownership.
Compliance, Fair Lending, and Tribal Sovereignty
Lending in Indian Country requires deep respect for tribal sovereignty. Tribes are independent sovereign nations with the inherent authority to govern their internal affairs, establish tribal courts, and regulate reservation land.
Because state courts generally lack jurisdiction to foreclose mortgages on trust land, lenders must navigate tribal courts and specific tribal civil jurisdiction codes. This is why we work closely with tribal housing authorities to ensure that all mortgage agreements respect local laws, foreclosure ordinances, and tribal customs, maintaining absolute compliance and fair lending practices.
Frequently Asked Questions about the Native American Home Purchase Process
Can I use a Section 184 loan to buy land and build a home?
Yes! The Section 184 program features a highly convenient single-close construction-to-permanent loan. This allows you to finance both the purchase of the land (or the leasehold setup) and the construction costs under a single loan with one closing, saving you thousands of dollars in closing costs.
Do I have to live on a reservation to qualify for Native American home loans?
No. While the Section 184 program was built to support reservation lending, it is fully eligible for use on fee simple land in thousands of approved counties across the United States, including major parts of Arizona, New Mexico, Utah, and Colorado.
How does the Bureau of Indian Affairs (BIA) affect my mortgage timeline?
If you are buying on trust land, the BIA must issue a Title Status Report (TSR) at both the beginning and the end of the loan process. Because these reports require manual processing by BIA staff, trust land transactions generally take longer to close than fee simple transactions. Working with a specialized lender who knows how to coordinate with the local BIA agency can significantly speed up this timeline.
Conclusion
The Native American home purchase process may have its fair share of legal and administrative hurdles, but they are far from insurmountable. With programs like the Section 184 loan, low down payment requirements, and extensive down payment assistance grants, the dream of homeownership is well within your reach.
Securing a home is more than just finding a place to live; it is a vital step toward closing the homeownership gap, establishing intergenerational stability, and building lasting wealth for your family and community.
At Native American Home Mortgage, we specialize in guiding tribal members through every step of this journey. Whether you are looking to buy on trust land or fee simple land in Arizona, New Mexico, Utah, or Colorado, we are here to help.
Ready to take your first step toward homeownership? Visit Native American Home Mortgage today to connect with our expert team and begin your application.