How a 203k FHA Loan Helps You Buy and Repair a Home
A 203k FHA loan lets you combine a home’s purchase price or refinance balance and eligible repair costs into one FHA-insured mortgage. It is designed for owner-occupied homes that need work, from a roof or HVAC replacement to larger structural repairs.
Before you apply, take these three steps:
- Decide whether your project is Limited 203(k) work – non-structural repairs up to $75,000 – or a Standard 203(k) project for major or structural rehabilitation.
- Confirm the property will be your primary residence and is generally at least one year old.
- Get detailed bids from qualified contractors and work with an FHA-approved lender that offers 203(k) financing.
The renovation funds do not arrive as cash in your bank account. They are held in escrow and released to contractors as completed work is inspected. FHA baseline rules generally allow a 3.5% down payment with a credit score of 580 or higher, though individual lenders may require higher scores or set other guidelines.
For Native American homebuyers and homeowners who feel overlooked by conventional lenders, understanding these rules can make a fixer-upper or needed repair feel more achievable. A 203(k) loan has paperwork, deadlines, and contractor oversight, but it can replace separate purchase and renovation loans with one long-term mortgage.
I am Dale Gremillion, a Senior Loan Officer and Producing Branch Manager with more than 25 years of residential lending experience across FHA, conventional, VA, USDA, HUD 184, and renovation financing. I help borrowers assess whether a 203k FHA loan fits their property, budget, and homeownership plans before they take on a rehabilitation project.
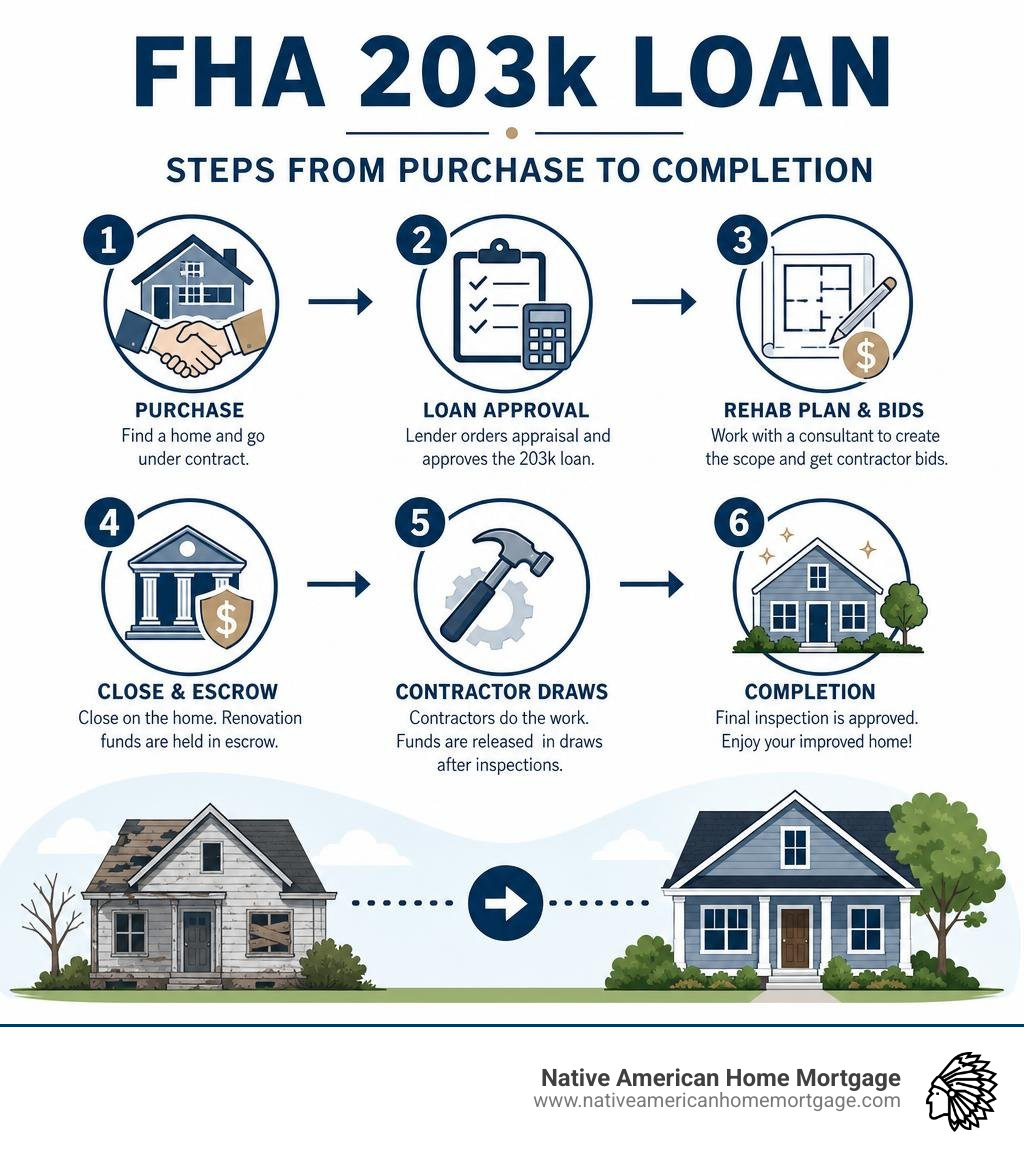
Understanding How the 203k FHA Loan Program Works
When buying a fixer-upper, traditional financing often hits a wall. Standard mortgage guidelines require a property to meet Minimum Property Standards (MPS) before closing. If a home has a failed heating system, damaged roof, or broken plumbing, a regular loan will likely be denied.
The 203(k) Rehabilitation Mortgage Insurance Program solves this issue. Backed by the Federal Housing Administration (FHA) under HUD Handbook 4000.1, this program allows lenders to insure the mortgage before repairs are finished.
Whether you are purchasing an existing property or executing a rate-and-term refinance to repair your current home, the financing rolls your purchase (or payoff balance) and anticipated renovation costs into one loan with a single monthly payment.
FHA 203(k) loans are strictly reserved for primary residences. Pure real estate investors looking to flip houses are not eligible.
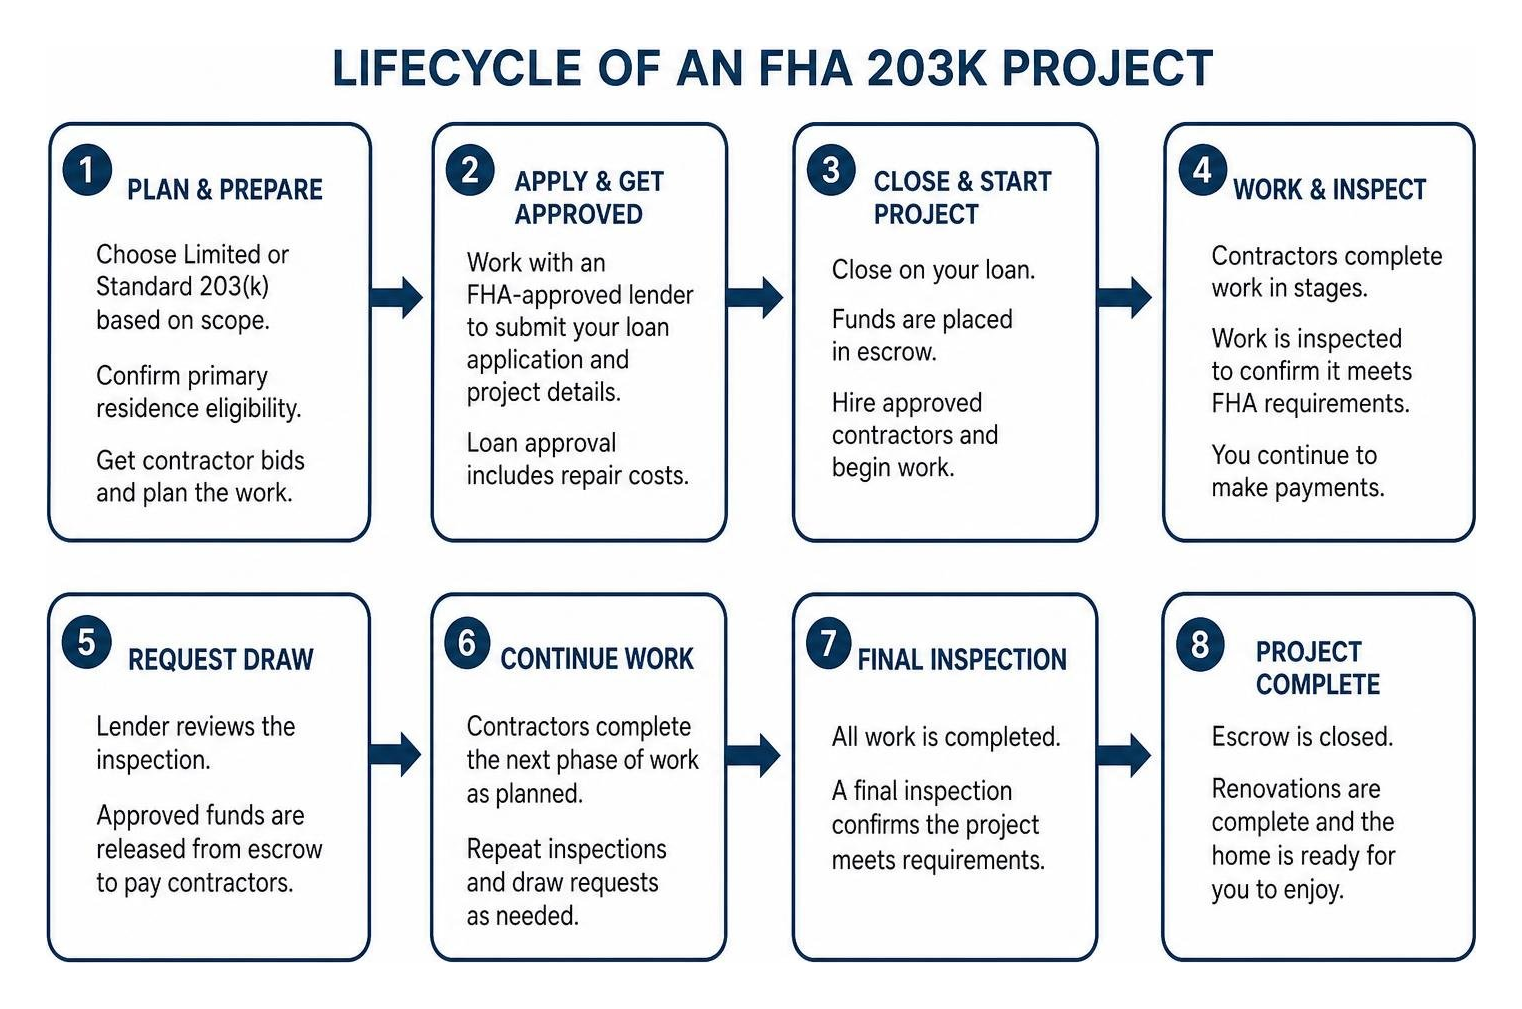
Standard vs. Limited 203(k): Key Differences
The program is divided into two tracks: the Standard 203(k) and the Limited 203(k) (historically referred to as the Streamline 203k). Choosing the right path depends entirely on the scope of work.
| Feature | Limited 203(k) | Standard 203(k) |
|---|---|---|
| Repair Cost Limit | Up to $75,000 | Minimum $5,000 up to local county loan limit |
| Structural Alterations | Strictly prohibited | Allowed (additions, load-bearing walls, foundations) |
| HUD 203(k) Consultant | Optional (lender discretion) | Mandatory |
| Project Timeline | Must complete within 9 months | Must complete within 12 months |
| Displacement Limit | Home must be habitable; max 30-day displacement | Can finance up to 12 months of mortgage payments if uninhabitable |
| Architectural Exhibits | Basic contractor bids | Detailed architectural blueprints and work write-ups |
The Limited 203(k) is designed for non-structural, cosmetic updates such as kitchen modernizations, new siding, flooring, and roof replacements. In contrast, the Standard 203(k) handles major structural alterations, room additions, load-bearing modifications, or full reconstructions where an existing foundation remains intact.
Modern Program Enhancements and Policy Updates
HUD modernized the 203(k) program under Mortgagee Letter 2024-13. These updates addressed long-standing friction points for both borrowers and contractors:
- Increased Limited 203(k) Cap: The rehabilitation limit under the Limited program was increased from $35,000 to $75,000 nationwide.
- Extended Completion Timelines: The Standard 203(k) completion window was extended to 12 months (up from 6 months), while the Limited 203(k) window was extended to 9 months (up from 6 months).
- Mortgage Payment Reserves: Standard 203(k) borrowers can now finance up to 12 months of mortgage payments into their loan if the home cannot be occupied during construction (up from the previous 6-month limit).
- Expanded Displacement Threshold: Limited 203(k) projects now permit home displacement of up to 30 days during rehabilitation (up from 15 days).
- Consultant Fee Financing: FHA-approved 203(k) consultant fees can now be financed across both programs.
Borrower and Property Qualification Guidelines
Qualifying for an FHA 203(k) mortgage requires meeting baseline FHA financial standards alongside specific property eligibility rules.

Borrower Eligibility and 203k FHA Loan Guidelines
FHA underwriting provides flexible credit and down payment guidelines:
- Credit Score Tiers: Borrowers need a minimum credit score of 580 to qualify for the 3.5% down payment option. A score between 500 and 579 requires a 10% down payment.
- Debt-to-Income (DTI) Ratios: The benchmark DTI ratio is 43%, though Automated Underwriting System (AUS) approvals may accept DTIs up to 50% or higher with strong compensating factors.
- Seasoning Rules: Borrowers must generally be three years removed from a prior foreclosure or bankruptcy discharge.
- Lender Overlays: Individual lenders often enforce overlays, such as requiring a minimum credit score of 620 or 660.
For Native American borrowers evaluating overall financing options, reviewing the complete guide to Section 184 loan qualifications and guidelines is a helpful way to compare down payments, loan limits, and mortgage insurance terms across government programs.
Property Eligibility and Eligible Improvements
The target property must be an existing residential structure completed for at least one year. Eligible property structures outlined in 203(k) Rehabilitation Mortgage Insurance Program Types include:
- 1-to-4 unit family dwellings
- Condominium units (interior renovations only; max 5 units or 25% of the association undergoing work simultaneously)
- Manufactured homes (built after June 15, 1976, affixed to a permanent foundation, and titled as real property)
- Mixed-use properties (must be at least 51% residential in square footage)
- Properties adding or updating Accessory Dwelling Units (ADUs)
Prohibited Improvements: Luxury items are strictly barred. You cannot finance new in-ground swimming pools, tennis courts, outdoor kitchens, or gazebos. However, existing swimming pools with structural damage can be repaired or removed using loan proceeds.
The Renovation, Escrow, and Contractor Draw Process
Managing the construction phase requires clear communication between the borrower, lender, contractor, and 203(k) consultant.

Contractor Hiring and Draw Schedule
All renovation work must be completed by licensed, insured, and experienced contractors.
- Detailed Line-Item Bids: Contractors must provide comprehensive bids breaking down labor, materials, and soft costs.
- DIY Restrictions: FHA regulations generally prohibit do-it-yourself (DIY) labor. Even licensed tradespeople working on their own homes cannot be reimbursed for labor costs, only verifiable material expenses.
- Initial Draw: For Standard 203(k) loans, lenders can disburse an initial material draw of up to 50% for specialized or custom-ordered supplies.
- Milestone Inspections: Contractors request draws as distinct project phases are completed. An inspector or consultant visits the site to verify progress before escrow funds are released.
- Final Release: Once all work passes final inspection, the borrower and consultant sign a final repair release letter, closing the escrow account.
Contingency Reserves and Uninhabitable Property Reserves
Unforeseen issues often arise when opening up walls in older properties. To prevent funding shortfalls, FHA mandates a contingency reserve of 10% to 20% of the total repair costs. If structural complications, outdated wiring, or hidden plumbing leaks are discovered during construction, contingency funds cover the added expense without derailing the mortgage.
If the property is uninhabitable during major Standard 203(k) repairs, borrowers can roll up to 12 months of mortgage payments (principal, interest, taxes, and insurance) into the total loan balance. This reserve covers monthly payments while you maintain alternative living arrangements.
Total loan amounts are evaluated against local FHA limits and cannot exceed the lesser of:
- The pre-renovation value plus repair costs, or
- 110% of the projected After-Renovation Value (ARV).
Evaluating Renovation Financing and Program Alternatives
Selecting the right renovation financing depends on your credit profile, desired scope of work, and program eligibility.
Pros and Cons of Choosing a 203k FHA Loan
Understanding the trade-offs helps you determine if an FHA 203(k) mortgage aligns with your timeline and financial goals.
Advantages:
- Low Down Payment: Finance purchase and rehab costs with as little as 3.5% down.
- Consolidated Financing: A single monthly payment replaces expensive, short-term personal loans or credit cards.
- Immediate Equity: Modernizing an outdated home creates instant post-renovation home equity.
- Flexible Credit Underwriting: Accessible credit score benchmarks starting at 580.
Disadvantages:
- Mortgage Insurance: Requires both an upfront Mortgage Insurance Premium (UFMIP) of 1.75% and an annual monthly MIP.
- Administrative Requirements: Involves contractor background checks, draw inspections, and consultant oversight.
- Timeline Constraints: Strict deadlines require work to start within 30 days of closing and finish within 9 to 12 months.
Comparing 203(k) Financing with Construction and Government Loans
Traditional construction loans typically operate as a “two-time close” structure. Borrowers take out a high-interest, short-term construction bridge loan that converts to a permanent mortgage once construction finishes—requiring two separate loan closings and higher closing costs.
By comparison, an FHA 203(k) loan provides a single closing with long-term fixed rates from day one.
For qualifying Native American and Alaska Native borrowers, comparing FHA financing with Indian loan guarantee options is an essential step. Reviewing FHA and Section 184 your guide to the Indian loan guarantee program can help you evaluate lower monthly guarantee fees and flexible underwriting across both options. You can also explore a complete guide to Native American home loans and buyer programs to understand how tribal trust land and off-reservation properties differ during rehabilitation.
Frequently Asked Questions About the FHA 203(k) Program
Can I complete the renovation work myself under an FHA 203(k) loan?
FHA guidelines generally require work to be completed by licensed and insured general contractors. While HUD permits self-help under rare circumstances for certified professionals, lenders rarely approve sweat equity. Borrowers cannot be reimbursed for their own labor, making independent contractors the standard requirement.
What are the maximum FHA loan limits for 2026?
For 2026, the baseline FHA single-family loan limit for low-cost areas is $541,287, while high-cost areas reach up to $1,249,125. Multi-unit properties (2-4 units) carry higher borrowing limits. Your total loan balance (purchase price plus renovation costs and contingency reserves) must remain within the limit for your specific county.
How long do borrowers have to finish home repairs?
Under updated guidelines, Limited 203(k) projects must be completed within 9 months of loan closing. Standard 203(k) projects allow up to 12 months. All rehabilitation work must formally begin within 30 days of closing, and work cannot cease for more than 30 consecutive days during the project.
Conclusion
An FHA 203(k) rehabilitation loan provides a practical pathway to purchasing and revitalizing older homes that traditional financing cannot accommodate. By combining your purchase or refinance balance and repair budget into a single long-term mortgage, you can build immediate equity while modernizing a home to fit your lifestyle.
Navigating contractor bids, HUD consultant reports, and escrow draws requires experienced guidance. If you are ready to evaluate your renovation options, we invite you to explore home financing options and begin your pre-approval process with our dedicated team today.