Cherokee Nation Mortgage Assistance: A Path to Homeownership
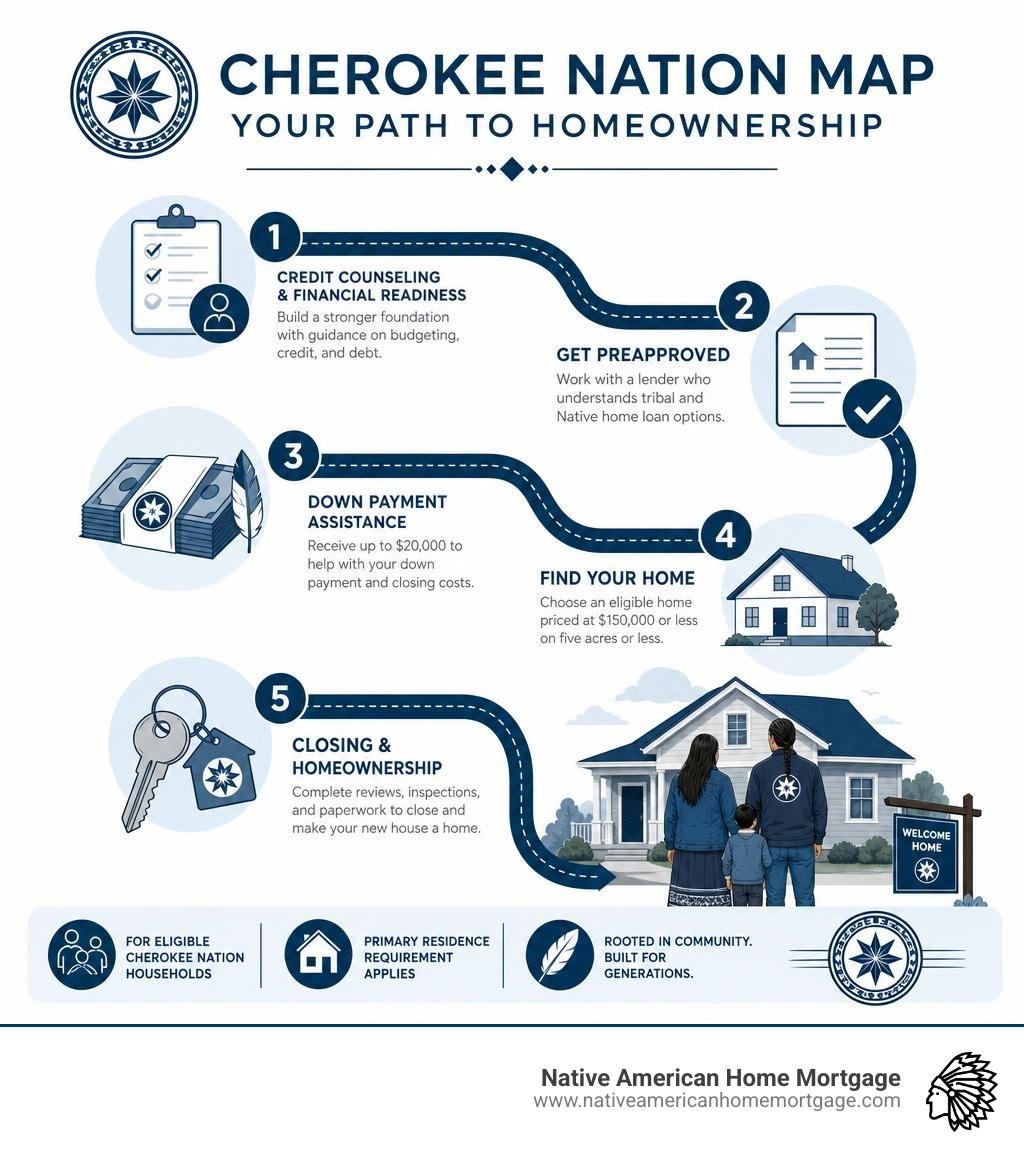
The Cherokee Nation Mortgage Assistance Program (MAP) can provide eligible households with up to $20,000 in down payment assistance to buy a home. It is designed to pair financial coaching, credit improvement, and mortgage financing so buyers can qualify for a home loan and afford the upfront costs.
Before you start home shopping, take these steps:
- Confirm that your household meets tribal membership, first-time buyer, and Cherokee Nation jurisdiction requirements.
- Work with MAP staff on budgeting, debt reduction, and credit readiness.
- Get pre-approved with a lender that understands tribal and Native home loan options.
- Choose an eligible property – generally priced at $150,000 or less and on five acres or less.
- Complete required reviews, inspections, and owner-occupancy paperwork before closing.
MAP is not a mortgage loan by itself. It is assistance that may work alongside financing such as a conventional mortgage or a HUD Section 184 loan. The assistance is generally tied to living in the home as your primary residence; leaving early can trigger a prorated repayment requirement.
For Cherokee families who have felt overlooked by conventional lenders, this program offers more than help with a down payment. Its counseling and financial-literacy support can help applicants build credit, lower debt, and make a sustainable plan for ownership.
I am Dale Gremillion, a Senior Loan Officer and Producing Branch Manager with more than 25 years of residential lending experience, including Conventional, FHA, HUD 184, VA, and USDA financing. I help buyers understand how the Cherokee Nation Mortgage Assistance Program may fit with the right mortgage strategy before they make an offer.
Understanding the Cherokee Nation Mortgage Assistance Program
Administered by the Housing Authority of the Cherokee Nation (HACN) in coordination with the Cherokee Nation Commerce Group, MAP modernizes tribal housing solutions. For decades, tribal entities relied strictly on direct construction models that produced houses slowly and resulted in multi-year waiting lists. Under that legacy format, only a fraction of hopeful buyers ever reached the closing table.
By shifting public investment into down payment grants and personalized credit counseling, the Cherokee Nation transformed its housing impact. Reporting by ICT News on how Cherokee Nation Helps Hundreds of Families Achieve Home Ownership highlights the scale of this change: tribal officials estimate that this approach allows more than six times as many people to own a home for the same funding outlay compared to direct building.
Over a five-year stretch, MAP assisted more than 5,000 citizens with credit repair, budgeting, and debt management, enabling more than 1,700 families to secure their own properties. Under the older building system, only around 600 families would have entered homes in that same timeframe. Overall, Cherokee housing initiatives have helped nearly 28,000 families secure safe, dependable housing tailored to their needs.
Core Benefits of the Cherokee Nation Mortgage Assistance Program
The centerpiece of MAP is a direct financial grant of up to $20,000 applied toward your home purchase. These funds can be allocated toward required down payments, allowable closing costs, and principal reductions.
Key advantages include:
- PMI Elimination or Reduction: Putting down a larger upfront amount reduces your loan-to-value ratio. Reaching a 20% down payment threshold removes Private Mortgage Insurance (PMI) on conventional loans entirely, saving buyers roughly $80 to $100 per month on a standard entry-level property.
- Forgivable Terms: The assistance is structured as a forgivable grant secured by a soft second lien. If you maintain the property as your primary residence for a 10-year term, the balance forgives completely—meaning zero monthly repayments on the grant.
- Prorated Repayment: Should you sell the home or convert it into a rental prior to the 10-year mark, a prorated payback mechanism applies, ensuring grant money returns to support other tribal members.
- Wealth Retention: Combining grant assistance with sustainable long-term financing promotes unlocking financial growth in Indian Country through native loans and grants, allowing buyers to build real equity from day one.
Eligibility and Household Income Guidelines
To maintain program integrity and direct tribal resources where they have the greatest impact, applicants must meet specific qualification rules:
- Tribal Affiliation: While Cherokee Nation citizens are given preference, the head of household or spouse may be an enrolled citizen of any federally recognized tribe.
- Income Limits: Total household earnings cannot exceed 100% of the National Median Income or 150% of the Area Median Income (AMI), whichever figure is higher based on current HUD calculations.
- First-Time Homebuyer Rule: Borrowers must generally be first-time buyers who have not owned a residential property within the past three years.
- Program Exceptions: The Housing Authority provides sensible exceptions for applicants who previously owned only a mobile home or those who lost previous housing due to documented domestic violence.
Understanding these benchmarks is essential when researching how to secure Native American housing grants this year.
Property and Loan Requirements for MAP Buyers
MAP funding comes with clear guidelines designed to keep monthly payments manageable and ensure families buy structurally sound, safe properties:
- Maximum Purchase Price: The property sales price cannot exceed $150,000.
- Acreage Limit: The land parcel must be five (5) acres or less.
- Geographic Boundaries: The home must be situated within the Cherokee Nation’s 14-county jurisdictional territory in northeastern Oklahoma.
- Property Standards: Single-family fee-simple residences, modular builds, and qualifying townhomes are permitted. Raw land purchases, speculative investments, and commercial buildings do not qualify.
- Inspections and Environmental Reviews: HACN conducts a mandatory environmental assessment and home inspection before clearing funds to ensure no deferred maintenance or environmental hazards threaten the buyer’s investment.
Aligning property search criteria with these metrics accelerates your path toward Native American home loan approval.
How to Apply for the Cherokee Nation Mortgage Assistance Program
Navigating the application process is straightforward when your documents are organized in advance.
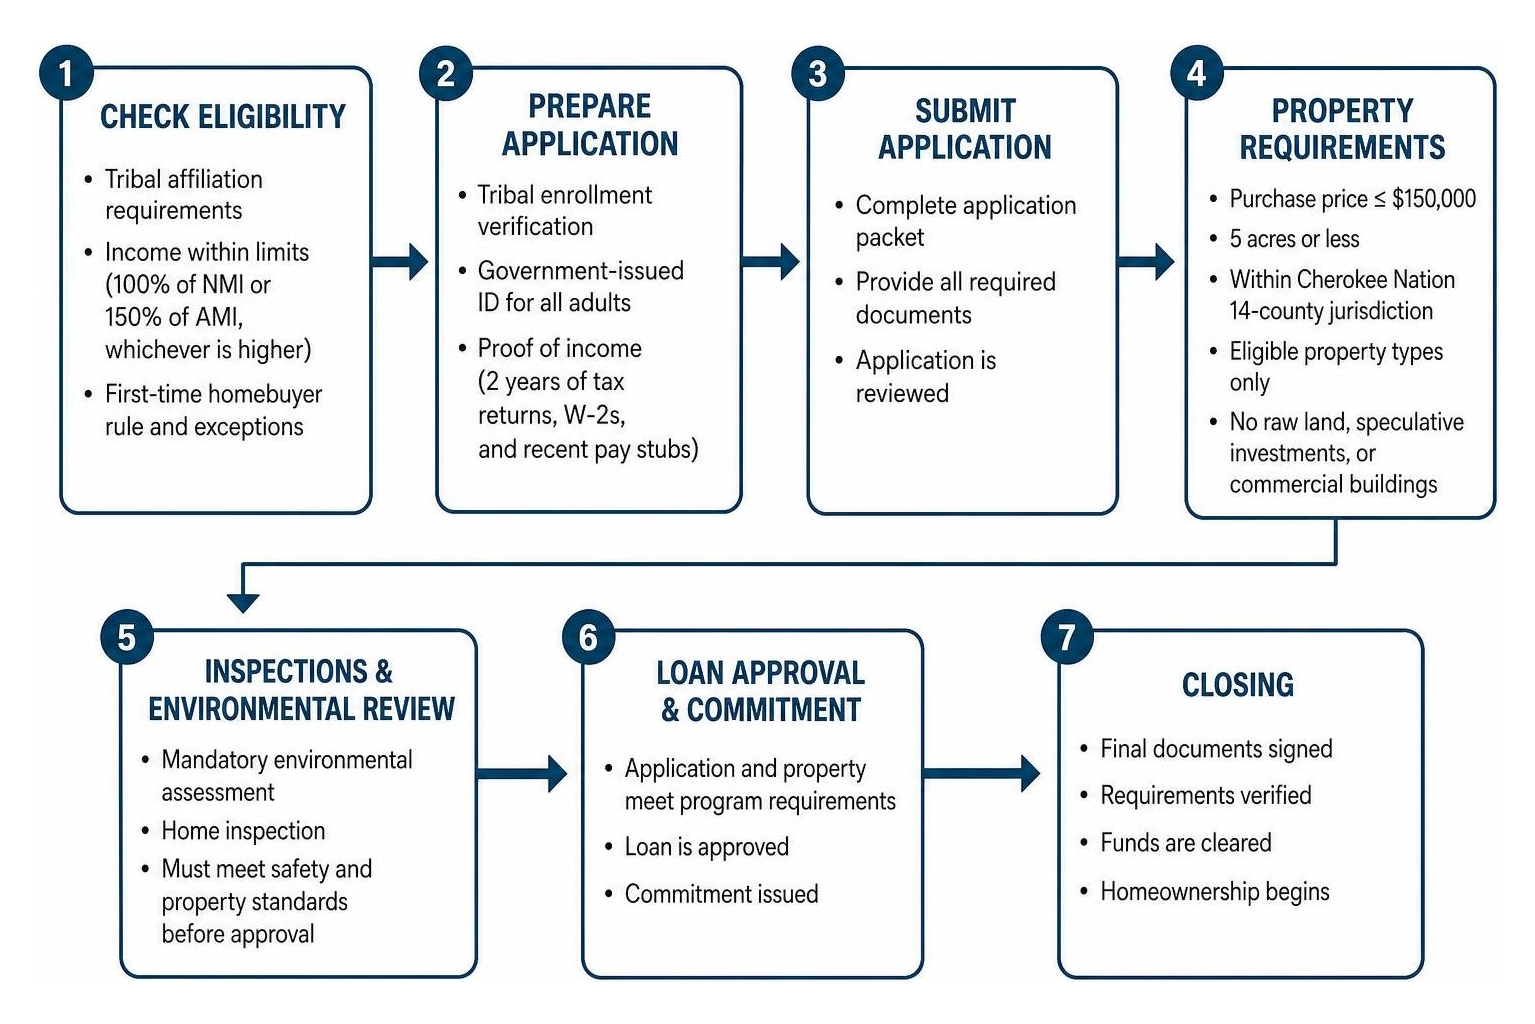
To initiate an application, prepare a packet containing:
- Tribal enrollment verification (CDIB card or official tribal citizenship documents).
- Government-issued identification for all adult household members.
- Proof of income, including the last two years of federal tax returns, W-2 forms, and recent pay stubs.
- Income declarations completed by all household members aged 18 and older.
- Recent bank statements detailing liquid assets.
- Credit reports or written disclosures regarding outstanding obligations.
Completed packets can be mailed to the HACN MAP office (PO Box 1007, Tahlequah, OK 74465) or delivered directly to regional Housing Authority service centers in Tahlequah, Catoosa, Sallisaw, or Jay.
Credit Coaching and Debt Reduction Support
Unlike rigid commercial lending channels, MAP focuses on long-term preparation. If an applicant has past credit blemishes, collections, or high debt balances, they are paired with a dedicated self-sufficiency counselor.
These counselors work alongside you to:
- Build a customized monthly household budget.
- Review your credit history and identify errors for dispute.
- Negotiate and settle outstanding debt balances systematically.
- Complete certified homebuyer education courses covering purchase contracts, home maintenance, and mortgage mechanics.
This educational framework equips buyers with practical budgeting skills so they can manage mortgage payments without financial strain.
Comparing MAP with Other Native American Homeownership Programs
Tribal buyers often evaluate multiple financing pathways to determine the lowest total cost of borrowing. Finding the right fit depends on whether you are buying on reservation land, living outside tribal boundaries, or seeking special veteran terms.
| Feature | Cherokee Nation MAP | HUD Section 184 Loan Guarantee | USDA Rural Development (Sec. 502) | VA Native American Direct Loan (NADL) |
|---|---|---|---|---|
| Primary Purpose | Down payment & closing cost grant | 100% government-guaranteed mortgage | Direct/guaranteed rural mortgage | Direct mortgage for Native veterans |
| Max Assistance / Loan | Up to $20,000 grant | Varies by county loan limits | Based on repayment capacity | Conforming loan limits |
| Down Payment Requirement | N/A (Provides down payment) | 2.25% (over $50k) / 1.25% (under $50k) | 0% down payment | 0% down payment |
| Tribal Membership | Enrolled member of any recognized tribe | Enrolled member of any recognized tribe | Open to general public (Native preference) | Native veteran or spouse |
| Repayment Terms | Forgivable after 10 years | 30-year fixed mortgage | 33 to 38-year fixed terms | 30-year fixed mortgage |
| Geographic Limits | Cherokee 14-county jurisdiction | Nationwide in eligible counties | Designated rural areas | On tribal trust or allotted land |
Exploring these options helps buyers learn how to find Native American housing programs and financial support suited to their location and goals.
MAP vs. HUD Section 184 and Federal Loan Options
The HUD Section 184 Indian Home Loan Guarantee Program is a nationwide lending vehicle established by Congress in 1992. Backed by a 100% federal guarantee from HUD’s Office of Native American Programs, it allows participating lenders to offer low interest rates and reduced down payment requirements (as low as 2.25%) with no standard monthly private mortgage insurance.
A major advantage for tribal buyers is pairing programs: eligible borrowers can use MAP’s $20,000 grant to cover the down payment and closing costs on a HUD Section 184 mortgage. Furthermore, while MAP grant spending is confined to the Cherokee Nation reservation boundaries, Section 184 loans are available to at-large Cherokee citizens buying homes across hundreds of participating counties nationwide.
Understanding how to structure these products provides strong financing options when securing home loans for Native American buyers.
Additional Tribal Housing and Relief Services
Beyond mortgage origination grants, the Housing Authority of the Cherokee Nation provides comprehensive community housing support:
- Homeowner Assistance Fund (HAF): For citizens experiencing hardship, the HACN HAF Program offers relief for delinquent mortgages, property taxes, and homeowner insurance to prevent foreclosure.
- Elderly & Disabled Housing: Dedicated senior communities, such as the Dogwood Addition in Stilwell, OK, provide accessible rental options for vulnerable elders.
- New Subdivision Developments: Funded through the Housing, Jobs and Sustainable Communities Act, the Cherokee Nation constructs modern single-family subdivisions—including the Crittenden, Cherokee, and Warrior Additions—as well as multi-family rental duplexes in communities like Ochelata, OK.
- Home Rehabilitation Services: Emergency roof repairs, weatherization, and accessibility upgrades are available for income-qualifying homeowners across the reservation.
Frequently Asked Questions About Cherokee Mortgage Assistance
How much down payment assistance can I receive through MAP?
Eligible applicants can receive up to $20,000 in down payment and closing cost assistance. These funds are applied directly on the closing disclosure to satisfy down payment minimums, cover escrow setups, and reduce principal balances.
Do I have to repay the Cherokee Nation MAP grant?
No, provided you fulfill the residency term. The assistance is placed as a forgivable lien that reduces each year. If you live in the home as your primary residence for ten consecutive years, the loan is 100% forgiven with zero out-of-pocket repayment. If you sell or vacate earlier, you repay a prorated portion of the funds based on your remaining tenure.
Can citizens living at-large qualify for tribal housing programs?
MAP grant funding requires the purchased home to be located within the Cherokee Nation’s 14-county tribal boundaries in Oklahoma. However, Cherokee citizens living at-large outside Oklahoma can utilize federal programs like the HUD Section 184 Loan Guarantee Program to purchase single-family homes across approved counties nationwide.
Conclusion
The Cherokee Nation Mortgage Assistance Program creates real financial pathways for families seeking stable, independent homeownership. By pairing up to $20,000 in down payment grants with practical budgeting, credit counseling, and sensible property guidelines, MAP helps buyers transition smoothly from renting to owning.
Whether you plan to buy within the Cherokee Nation reservation or explore Native American lending options across other states, securing experienced mortgage guidance is the best first step. Connect with our lending team at Native American Home Mortgage to review your eligibility, explore HUD 184 options, and start your homeownership journey today.